-
Disney/ABC's Cheng is Confident About Broadband Video Advertising
Though broadcast TV networks have been aggressively pushing their shows online, there has been simmering angst about what impact this will ultimately have on their traditional economics.
I have explored this issue recently in "Does Broadband Video Help or Hurt Broadcast TV Networks?" and in two posts on Fox's "Remote-Free TV" initiative here and here. NBCU's CEO Jeff Zucker has helped to stoke this concern, publicly calling broadcasters' #1 challenge the risk of exchanging "analog dollars for digital pennies."
Thus I was both a bit surprised, but also encouraged, to hear Albert Cheng, Disney/ABC's EVP of Digital
 Media tell me in a recent briefing that despite the fact that online revenue per program per eyeball is currently less than it is for on-air, he's confident that online will eventually catch up and surpass on-air. I don't regard these comments as idle boasts. A thick PowerPoint deck covering its online video strategy, which Disney/ABC shared with me, reveals the meticulous thought and in-depth audience research that is guiding Disney's online video initiatives. Not to mention ABC.com is the most-used network web site.
Cheng is quick to point out that Disney/ABC has followed a careful and consistent strategy since it moved into online distribution a few years ago (note Disney/ABC was the first network to work with iTunes and first to offer programs for free. Other networks quickly followed). The focus has been on continued learning and refinement.
From a strategy standpoint, Disney/ABC's video player, powered by Move Networks, is the centerpiece. The focus is on delivering a high-quality, consistent user experience in which ads are engaging, but not intrusive. While other networks have received more ink for their syndication efforts Cheng is quick to point out that access to Disney/ABC's player has always been open, allowing other sites to refer their users, if not actually integrate the player.
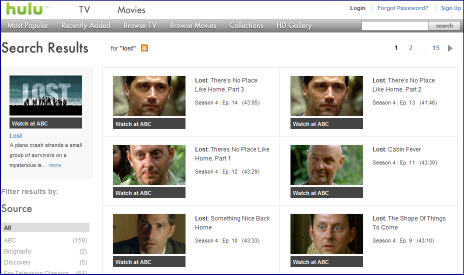
By making an RSS feed available of its online programs' meta-data, Cheng believes Disney/ABC can achieve much of what others gain through syndication deals (see how Hulu displays results for a "Lost" search below, subtly noting "Watch at ABC" This is the same concept I noted in my recent Hulu vs. Comcast post), while avoiding the downsides of ad sales conflicts, business rules implementation and delivery overhead.
By controlling their own ad inventory, Disney/ABC avoids the sometimes one-sided revenue sharing deals widely-discussed in the industry (Hulu alone is rumored to keep 90%) and the channel conflict that inevitably results from having two sales teams calling on the same media buyers. Cheng does see a role for online aggregators, but mainly for library or off-network product, especially as a backstop for traditional syndication.
Cheng's rationale for broadband's eventual revenue superiority to on-air ultimately boils down to this: since broadband can offer both superior targeting and engagement vs. on-air, by definition it deserves higher pricing. But getting to that vision from today's reality is where Disney/ABC's hard work of evangelizing to advertisers and ongoing testing is key (and where the company's recently announced "Ad Lab" comes in).
Here again, by controlling its own inventory and player experience, Cheng believes Disney/ABC is better positioned than other networks. He surmises that, public comments notwithstanding, other networks are not selling out their inventory and are getting lower CPMs than Disney/ABC. Maybe this helps explain the "analog dollars, digital pennies" angst?
Disney/ABC's efforts to fully monetized broadband delivery will be closely watched as an indicator of broadband's true impact on broadcasters. And while I believe Cheng's regard for broadband's potential is correct, broadcasters still face the very real headwinds of consumer distaste for ads in general, the proliferation of ad-skipping through DVRs, and the expectations being set with limited ads in current online implementations.
While I'm rooting for Disney/ABC and others to succeed in broadband video advertising, I think they have their work cut out for them.
What do you think? Post a comment and let everyone know!
Categories: Advertising, Broadcasters
-
Visible Measures: Ultimate Broadband Video Measurement
If you've ever hungered for insight about a specific video's performance beyond just how many views it has received, Visible Measures is a company after your heart. An independent firm that measures the reach and engagement of broadband video across the Internet, VM heralds an era of ultimate insight into how each and every video performs when it enters the Internet's fast-moving current.
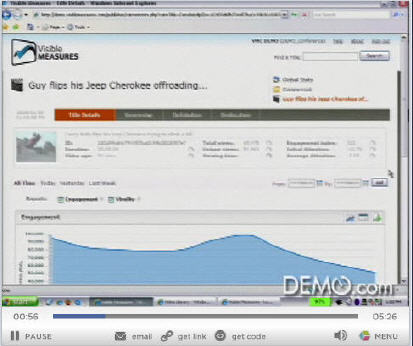
By integrating its code with the video player, VM collects data on session length, drop-out points, rewind activity, click-throughs, viral distribution, geographic usage and other metrics. Think of VM as "big brother-esque" (in a positive way) in tracking a video's "true reach" as VM puts it, supplying a dizzying array of data to content providers and advertisers. The data is presented in intuitive, graphical formats that analysts can parse and sort to understand the video's ROI and what can be done to improve performance next time around. The company is already tracking over 80 million videos in its database.
I recently spent time with Matt Cutler, VM's VP of Marketing and Analytics who gave me a demo of the system and how it's being brought to market. VM is targeting established and early stage media companies, advertisers and ad agencies, all of whom have a critical stake in developing business cases for video deployments and ad campaigns. VM's tracking capabilities are especially meaningful given how pervasive the "syndicated video economy" is becoming.
None of this is to suggest that VM's data will replace programmers' and advertisers' creative instincts, but it would surely provide some real world augments to help offset the inherent guesswork involved in the creative process. (for more specifics about how VM works, see the below video from DEMO '08)
For advertisers specifically, today VM is announcing both its "VisibleCampaign" solution to measure ad campaigns' performance and also a collaboration with Dynamic Logic to track how these campaigns affect a brand's perception. Both initiatives are important in helping advertisers and agencies gain more insight about the broadband video medium and why it's important to invest. As someone who has expressed concern that the broadband ad business needs to mature quickly to support the myriad startup and established media companies relying on it, VM's will surely help decision-makers across the board gain comfort in shifting over more of their budgets.
VM is a perfect example of innovation needed to help optimize a new medium as it takes root. The company has raised $19 million through three rounds and is based in Boston. Based on what I've seen I'm quite enthusiastic about its odds of success.
Categories: Advertising, Startups, Technology
Topics: Dynamic Logic, Visible Measures
-
Hulu Out-Executing Comcast in On-Demand Programming?
The crew over at Hulu must be gleefully fist-bumping each other this week as Hulu scored a key strategic and public relations coup in adding to its lineup two of Comedy Central's most popular programs, "The Daily Show with Jon Stewart" and "The Colbert Report." Though officially positioned as a test, Hulu still deserves big-time kudos as the deal is an endorsement of its value proposition.
The deal and Hulu's execution illustrate a larger point that I've been making for a while: one of broadband's three key disruptions is that it enables new aggregators to gain an edge on larger incumbents by changing the dynamics of competition. To be more specific, in this case, I think that Hulu has out-executed Comcast, America's #1 cable operator by delivering new value to consumers and gaining important PR momentum. Here's why:
Fancast, which is Comcast's online portal (in beta), actually announced a deal with Comedy Central back on May 19th for access to these same programs and others. Yet go to Fancast and search for "Daily Show" and, as shown below, you won't find any Daily Show full episodes available, just an assortment of short clips and times when it's on TV. A Comcast spokesperson told me that Comcast's implementation is imminent, but its delay in getting the programs up and running is accentuated when you consider that Comedy Central must have done its distribution deal with Fancast BEFORE its deal with Hulu.
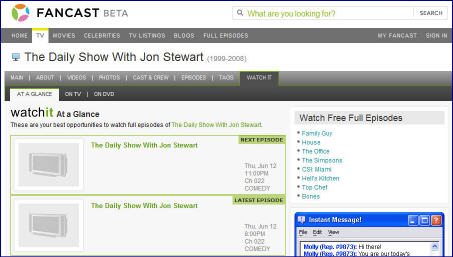
Second, and more concerning is that, as a Comcast digital subscriber, when I tried to find The Daily Show and Colbert in Comcast's VOD menu, all that is available are five older Colbert clips and 1 older Daily Show clip. My guess is these haven't been updated in a while. No full-length Daily Show or Colbert programs are available at all in VOD.
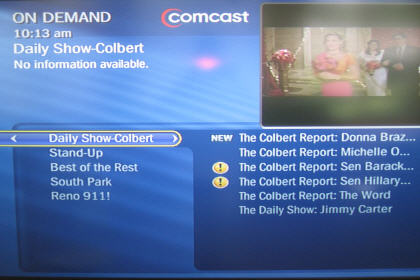
While the Comcast spokesperson told me that the company works closely with its programming partners like Viacom to figure out the optimal mix of programming to make available on VOD, I think an unavoidable conclusion here is that Comcast (and other cable operators) is constrained by its inability to monetize VOD programming with advertising (what this week's "Project Canoe" is meant to address) and to easily add new programming on the VOD menu. These programming gaps create opportunities for upstarts like Hulu to capitalize on.
It may be unfair to zero in so narrowly on Comcast's execution with Daily Show/Colbert, yet things weren't much different when I searched for MTV's popular "The Hills" on Hulu, Fancast and Comcast's VOD. While Hulu doesn't appear to have a deal for full episodes of "The Hills" it masks this cleverly by providing thumbail images and easy navigation back to MTV's site where the video lives, for over 50 episodes (this is tactic Hulu uses for ABC's shows as well). On the other hand, Fancast displays just 5 full episodes, 2 from this season and 3 from last. And on VOD there are also just 5 episodes, though all from this season.
I think it's pretty significant that Hulu, a site that only went live 3 months ago can not only gain access to hit Comedy Central programs like Daily Show/Colbert, but can execute quickly. Hulu is using its advantages - flexible technologies, interactive features (clipping, embedding, sharing), monetization capability, savvy PR and startup pluck to compete with far-larger incumbents like Comcast.
Of course Comcast racks up billions of VOD views each year and has vast resources, making it an important player in on-demand programming. Yet Hulu has managed to make Comcast's advantages look a little less intimidating. I asked the Comcast spokesperson about this. She acknowledged Hulu's progress, but maintained that Comcast believes its mulit-platform approach is stronger.
In the big picture that's true, but when it comes to winning consumers' hearts and minds, it's often execution, not broad strategy that carries the day. And don't forget, when Hulu is unshackled from the PC - with its content freely riding Comcast's broadband pipes all the way to the TV - execution will matter even more.
This week Hulu provided a textbook example of how broadband-only aggregators can gain a foothold against well-established incumbents. Comcast and other incumbents should be taking notice and getting their game on.
What do think? Post a comment and let everyone know!
Categories: Advertising, Aggregators, Cable Networks, Cable TV Operators
Topics: Comcast, Comedy Central, Fancast, Hulu, The Colbert Report, The Daily Show, Viacom
-
More on Heavy's Spinout of Husky Media
Late last week, news broke that Heavy Media, which operates Heavy.com, one of the leading destination sites for men 18-34 was spinning off its Husky Media unit as a standalone ad management and network company. I found the deal intriguing and followed up with David Carson, co-CEO to learn more and see how it plays into larger trends I've been tracking.
 Broadband ad networks already compete vigorously with each other to build out their publisher networks and cultivate brands and agencies to obtain a share of their spending. The networks are continuously enhancing their technology and trying to optimize their various ad units to demonstrate the superiority of their approach. And as I recently wrote in "Tremor, Adap.tv Introduce New Ad Platforms," some firms are now enabling ad aggregation in an effort to improve their publishers' effective CPMs.
With this context in mind, a key question is "does the world really need another video ad management and network?" David patiently explained that they've received a lot of outside interest in their units, namely the "barn doors" that are shown before the video plays, the subsequent skin that remains on the sides while the video plays, and the playlist-like queuing of video with ads judiciously interspersed (which Heavy calls its Video Guide). Heavy has avoided pre-rolls entirely. This interest spurred them to separate Husky.
David believes that each of these units offers superior value. As compared with pre-rolls, where David said "bounce" or early termination rates can be 50% (resulting in the actual content never being seen), with Husky's approach, there's a 90% completion rate, and particularly when users come through the Husky "Video Guide", the number of videos consumed can be 3-6 times greater. David also said they're seeing click-throughs averaging 1.6%, above industry norms.
So of course the next question is, if these units perform so well, what's to stop others from introducing them as well? In fact, David would encourage this, as he believes it would help educate the market and maybe help establish these as preferred units. As long as Husky continues to get its fair share that would be a win. Husky has patents on the skin, and how it works with various video players.
David said investor meetings are underway and he anticipates the company completing its own financing. Husky will have its own separate management team. Heavy also announced last week a syndication deal for its Burly Sports show to CBSSports.com, and, no surprise, Husky will be the ad platform. To the extent that Heavy can do other syndication deals where Husky gets included, that will help it gain market share.
Clearly there continues to be a huge amount of experimentation in the broadband video ad market. The Husky deal further shows that sometimes developing technology for your a site's own use can, if successful, end up creating larger financial value.
Categories: Advertising, Deals & Financings, Indie Video
Topics: Adap.TV, CBSSports.com, Heavy.com, Husky, Tremor
-
Fox's "Remote-Free TV" Seems to Fall Short
Two-and-a-half weeks ago, in "Fox's 'Remote-Free TV': Broadband's First Adverse Impact on Networks" I asserted that Fox's decision to cut in half the number of ads it will include in two new programs was influenced by the limited ads shown in networks' broadband initiatives.
By giving "RFTV" a try, Fox was catching on to the idea that fewer commercial interruptions improves the
 viewer experience. I pointed out that the challenge RFTV posed is that cutting ad time in half means that Fox would have to double the CPMs it charged just to remain whole. Could Fox do that?
Yesterday's piece in Adweek provided at least a preliminary answer: No. Adweek, quoting unnamed media agency sources, reported that Fox is getting only a 35-40% premium for the "RFTV" ad inventory. If my math is right that would imply that Fox is grossing 30-33% less total ad revenue than it would have under its traditional ad model.
Broadcast networks, having moved much of their programming online, have engendered new viewer expectations for fewer ads. The early results from Fox's "RFTV" initiative may indeed be evidence that these new expectations are at odds with sustaining broadcasters' traditional margins and profits.
Categories: Advertising, Broadcasters
Topics: FOX
-
Video Aggregators Have Raised $366+ Million to Date
With this week's news that Veoh has garnered another $30 million in financing, by my count the total amount raised by the top broadband video aggregators now exceeds $366 million. The breakdown is below, according to publicly available data I've pulled together.
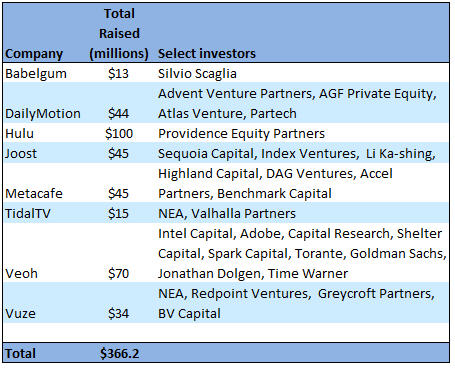
While definitions of who should be included in this category are admittedly fuzzy, I consider broadband aggregators to be companies that are providing a broad-based destination site that focuses mainly on professionally-created video. Often these sites include broadcast network and cable TV programming, but they don't have to. I'm sure plenty of readers have their own definitions and that I've overlooked some, so feel free to post a comment to add others to the list.
Savvy investors seem to have an enormous appetite for these kinds of companies. Veoh, with 28 million monthly unique visitors, and others have demonstrated their ability to attract lots of eyeballs. Yet all of these companies are solely reliant on advertising, and that of course makes begs the question how well these companies can convert their traffic to real revenue and therefore become profitable, sustainable businesses?
Since all of these companies are private it is hard to assess their momentum. Yet in a recent panel I moderated at Streaming Media East, Mike Henry, SVP of Ad Sales for Veoh explained the range of current challenges. Chief among them is getting traditional TV media buyers to clearly understand the broadband medium, how to buy into it and how to measure its performance. These are crucial matters since the biggest source of broadband ad dollars will no doubt come from brands shifting their TV spending to broadband.
Of course, to the extent that these companies can continue raising big money, they're buying themselves more runway. Complicating matters is that all of these sites live in the long shadow of YouTube, which alone still accounts for around 40% of all video views per month. Then there are big players like Yahoo, MSN and AOL and recent entrants like Adobe which are vying for their share of the video pie. But at some point these companies will have to show they can make money and survive.
With all these crosscurrents, it will be interesting to see how these companies' stories unfold.
Categories: Advertising, Aggregators, Deals & Financings
-
Where's Project Canoe's New CEO?
At the recent Cable Show in New Orleans, Comcast's president Steve Burke said that Project Canoe's new CEO would be announced on June 1. However, June 1 has come and gone without any news. Project Canoe, which Mugs covered for VideoNuze recently, is the cable industry's new interactive ad system, meant to draw national advertisers to cable's VOD and other advanced video delivery platforms. A rumor has circulated widely that David Verklin, former CEO of Aegis North America (a large advertising service firm) would get the nod, but nothing has been made official. I haven't heard what is causing the delay. If you know, post a comment...
Categories: Advertising, Cable TV Operators
Topics: Comcast, Project Canoe
-
May '08 VideoNuze Recap - 3 Key Topics
Looking back over two dozen posts in May and countless industry news items, I have synthesized 3 key topics below. I'll have more on all of these in the coming months.
1. Broadband-delivered movies inch forward - breakthroughs still far out
In May there was incremental progress in the holy grail-like pursuit of broadband-delivered movies. Apple established day-and-date deals with the major studios for iTunes. Netlix and Roku announced a new lightweight box for delivering Netlix's "Watch Now" catalog of 10,000 titles to TVs. Bell Canada launched its Bell Video Store, complete with day-and-date Paramount releases, with others to come soon. And Starz announced a deal with Verizon to market "Starz Play" a newly branded version of its Vongo broadband subscription and video-on-demand service.
Taken together, these deals suggest that studios are warming to the broadband opportunity. This is certainly influenced by slowing DVD sales. Yet as I explained in "iTunes Film Deals Not a Game Changer" and "Online Move Delivery Advances, Big Hurdles Still Loom" broadband movies are still bedeviled by a lack of mass PC-TV connectivity, no real portability, well-defined consumer behavior around DVDs and the studios' well-entrenched, window-driven business model. Despite May's progress, major breakthroughs in the broadband movie business are still way out on the horizon.
2. Broadcast TV networks are embracing broadband delivery - but leading to what?
Unlike the film studios, the broadcast TV networks are plowing headlong into broadband delivery, yet it's not at all clear where this leads. In "Does Broadband Video Help or Hurt Broadcast TV Networks" and "Fox's 'Remote-Free TV': Broadband's First Adverse Impact on Networks?" I laid out an initial analysis about broadband's pluses and minuses for networks. I'll have more on this in the coming weeks, including more in-depth financial analysis.
On the plus side, in "2009 Super Bowl Ads to Hit $3 Million, Broadband's Role Must Grow," "Sunday Morning Talk Shows Need Broadband Refresh" and "Today Show Interview with McClellan Showcases Broadband's Power," I illustrated some opportunities broadband is creating. On the other hand, "Bebo Pursues Distinctive Original Programming Model" and "More Questions than Answers at Digital Hollywood" explained how exciting new programming approaches are taking hold, challenging traditional TV production models. Broadcasters are in the eye of the broadband storm.
3. Advertising's evolution fueled by innovation and resources
Last, but hardly least, I continued on one of my favorite topics: the impact broadband video is having on the advertising industry. Over the last 10 years the Internet, with its targetability, interactivity and measurability has caused major shifts in marketers' thinking. With broadband further extending these capabilities to video, the traditional TV ad business is now ripe for budget-shifting. We'll be exploring a lot of this at a panel I'm moderating at Advertising 2.0 this Thursday.
In "Tremor, Adap.tv Introduce New Ad Platforms" and "All Eyes on Cable Industry's 'Project Canoe'" (from Mugs Buckley), key players' innovations were described along with how the cable industry plans to compete. Content providers are being presented with more and more options for monetizing their video, a trend which will only accelerate. Yet as I wrote in "Key Themes from My 2 Panel Discussions Last Week," many issues remain, and with so many content start-ups reliant on ads, there may be some disappointment looming when people realize the ad market is not as mature as they had hoped.
That's it for May. Lots more coming in June. Please stay tuned.
Categories: Advertising, Aggregators, Broadcasters, Cable TV Operators, Devices, Downloads, FIlms, Studios, Video Sharing
Topics: Adap.TV, Apple, Bell Canada, Canoe, iTunes, Netflix, Paramount, Roku, Starz, Tremor, Verizon, Vongo
-
Key Themes from My 2 Panel Discussions Last Week
Last week I moderated 2 panel discussions, one for Streaming Media East in New York, and the other for MITX, the Massachusetts Innovation and Technology Exchange, in Boston. In the former, "Reinventing the Ad Model Through Discovery and Targeting" and the latter, "Driving Audiences to Your Online Video Content: Strategies for Success in a Crowded Market" panelists discussed many of the key themes I continue observing in the broadband video market.
Early adopters are heaviest broadband usersDespite research that continues to show broadening adoption of broadband video usage (11.5 billion videos viewed in March, according to comScore), at SME, Nielsen's Jon Gibs confirmed that the vast majority of the market is still very casual users, with only 5-8% of overall users showing more habitual and long-form viewing. For many today, the viewing experience is still limited to watching a YouTube clip emailed to them or found in a friend's MySpace or Facebook page. Plus user attention spans remain short. At MITX, Visible Measures' Brian Shin showed how viewership drops off a cliff following the climactic moment of a hilarious user-generated clip. Broadband is driving significant behavioral change for a segment of the market, but transitioning to a heavily-used mainstream medium will take years.Video proliferatesNonetheless, the number and range of video producers continues to expand, as all kinds of organizations recognize that video is a totally new opportunity to connect with their audiences, whoever that may be. At the MITX event, panelists showed examples from politicians, cultural organizations, small businesses, schools, brands and users themselves. I've said for a while that we're entering a "golden age" of video, with a massive proliferation of the quantity and range of sources. The market is already well into this phase.Discovery is a huge problemWith this massive proliferation comes the huge problem of how users will actually find what they're looking for. At SME, Mike Henry from Veoh discussed promising results of Veoh's proprietary behavioral recommendation engine. At MITX, Tom Wilde from EveryZing showed how it can surface video for search engine discovery by using its speech-to-text engine; while Murali Aravamudan from Veveo explained how its algrorithms can quickly distinguish the video users are truly searching for. All of these approaches improve the users' experience. Yet what's equally clear is that, having never experienced the explosion of video choices we're now witnessing, it's impossible to know what will ultimately end up working. Discovery is an ongoing problem to be solved.Ad market still immatureLast but not least, for the many fledgling and established video providers relying on advertising, the good news is that there's a lot of buyer interest, but the bad news is that it's still a very immature market. At SME we discussed how many media buyers look at broadband video through their traditional TV lenses, leading to a focus on TV's "Gross Rating Points" or GRPs model. But this undervalues the real engagement opportunities that broadband enables. At MITX, Bob Lentz of PermissionTV discussed how broadband is changing the role of ad agencies, traditional stewards of the creative process, allowing them to now do much more. Advertising is the primary business model for content providers, yet the shift of dollars the medium is anything but straightforward.These were four of the key themes from these two sessions. There was plenty more information exchanged, if you're interested, drop me a line and I'll be happy to discuss.
Categories: Advertising, Events
Topics: EveryZing, MITX, Nielsen, PermissionTV, Streaming Media East, Veoh, Veveo, Visible Measures
-
All Eyes on Cable Industry's "Project Canoe"
To the disappointment of many, it looks like there won't be any big news about the cable industry's "Project Canoe" at the Cable Show convention in New Orleans this week.
Project Canoe is a high-profile partnership among the nation's six largest cable companies (Comcast, Time Warner Cable, Cablevision, Cox Communications, Charter Communications and Bright House Networks) to enable national interactive advertising campaigns to be executed across the companies' cable operations. The code-name Canoe is meant to emphasize that cable operators are working together in the same boat, so to speak.
For the past nine months, the partners' Canoe leads have been meeting weekly. Once a top secret initiative, Canoe's existence was leaked in a September, 2007 Wall Street Journal article. But since then there has been no new information, leading to speculation about how much progress has been made.
Yet Canoe remains a top priority throughout the industry, and for good reason. With big advertisers like GM and Intel shifting their once big-budgeted TV ad campaigns to the Internet in significant sums, it's key that the cable operators need to figure out a way to not only protect the $5 billion or so that they generate in spot-cable advertising today, but also to increase their piece of the $70 billion dollar TV ad spend or cut into other slices of the massive US total ad spend pie. The next 3-5 years will be critical as cable advertising, the Internet and broadband video jostle for advertisers' affections.
The buzz in New Orleans suggests advertisers and agencies are excited about Canoe, though its development seems slower than they prefer. Why the slow progress that's perceived? Several operators stated that integrating the infrastructure required to execute Canoe with cable's legacy systems is hard stuff. No doubt. Then of course there are other key priorities weighing on the industry resources, such as the February 2009 digital transition.
Meanwhile, the Internet and broadband video advertising continue steaming ahead, giving advertisers and their agencies the measurement and targetability that they yearn for on TV. Cable operators have been stymied in their ability to jointly offer advertisers easy access to a nationwide or near-nationwide footprint, especially critical for Video on Demand. Canoe addresses this and other opportunities, in part by creating a set of standards for all to follow.
The only Canoe "news" at this week's Cable Show came from Comcast's Steve Burke, who stated that a CEO would be announced on June 1. Comcast is a key player in Canoe, funding between $50-70 million of the $150 million initial investment. Rumors have swirled that David Verklin, who recently stepped down as CEO of Aegis North America (a large advertising services firm) will assume the position of CEO. If true, that could be the news to break on June 1.
For those of us who have been around the interactive advertising and TV mulberry bush for many years, Canoe's potential is exciting. But we're hoping that the Canoe gets it in gear. Paddle on, gang.
What do you think of Project Canoe's prospects? Post a comment now!
Categories: Advertising, Cable TV Operators
Topics: Aegis, Bright House Networks, Cablevision, Charter Communications, Comcast, Cox Communications, Project Canoe, Time Warner Cable
-
Fox's "Remote-Free TV": Broadband's First Adverse Impact on Networks?
One of the more interesting tidbits to come out of last week's upfront was Fox's "Remote-Free TV" initiative. In case you missed it, Fox Entertainment President Peter Liguori announced that two of the network's new programs, "Fringe" and "Dollhouse" will carry approximately half the typical amount of advertising. As a result, the programs will run as long as 50 minutes compared to the customary 42-44.
Why is Fox doing this and why does it matter? According to TV Week's coverage, Mr. Liguori said: "The broadcast business needs a jolt. This gives viewers one less reason to change the channel." The first statement is certainly true, but the second seemed off somehow. If the programming's really compelling, it seems unlikely that viewers are going to change the channel (when did you ever change the channel in the middle of "24" for example?).
Switching channels doesn't seem to be the issue; rather, I think the more pressing concerns behind RFTV are ad-skipping from DVR usage and broadband's growing influence. But on the DVR side, if I'm a viewer
 watching programs like these in recorded mode, are fewer pods or shorter ads going to make me any less inclined to hit the fast-forward button to skip the ads? Doubtful. I only need to retrain myself to hit the "play" button sooner.
If that's the case, then it seems to me that "RFTV" should be interpreted as a response to viewers' preference for broadband's "limited commercial interruptions" model. But when Fox cuts these programs' on-air ad time in half, it needs to double its fees per ad to remain even. Fox is now talking to advertisers to see if it can turn that goal into a reality. Maybe it can. Maybe it can't. If it can't, then these 2 new programs' on-air monetization will be lower than traditional expectations. Could this mean that "RFTV" may actually end up representing broadband's first demonstrably adverse impact on the network TV business? Quite possibly.
In my post last week, "Does Broadband Video Help or Hurt Broadcast TV Networks?" I argued that while broadband offers short-term benefits, in the long-term it's going to force broadcast TV networks to fundamentally adjust to different economics. Broadband's limited commercial interruptions means far fewer ad slots to monetize. RFTV may be a harbinger that this approach may now be coming to on-air as well.
Though broadband delivery is still nascent, its implications are far-reaching. In this case, having moved most of their prime-time programs online, networks now need to show it brings positive results. That will be interesting to watch. Longer-term may be nearer than I thought.
What do you think of Fox's "RFTV" initiative? And how does it impact the network's business? Post a comment and let everyone know!
Categories: Advertising, Broadcasters
Topics: FOX
-
Does Broadband Video Help or Hurt Broadcast TV Networks?
Yesterday's article in the NY Times, "In the Age of TiVo and Web Video, What is Prime Time?" was the latest of many about the changing landscape of broadcast network TV. An underlying question that receives a lot of attention, yet little in the way of clear-cut conclusions: Does broadband video help or hurt broadcast TV networks?
The jumble of conflicting data and opinions on this topic (as well as the related topic of DVRs' impact on the networks) is causing plenty of speculation during this important upfront week of when billions of dollars of networks' ads are bought and sold.
Here's a synopsis of how I think proponents of each would defend their answer:
Broadband video helps: The world is changing - consumers are more empowered than ever and it's pointless to resist. Broadband is a great way to catch up on episodes missed, conveniently sample programs, engender interactivity, transform viewers into viral promoters, etc. More exposure will translate into more on-air viewership. Plus as broadband audience size builds ad revenue will as well. Network programming is and always will be the most watched, most valued source of video entertainment and with broadband opening up all kinds of new revenue opportunities, there's ample reason to be optimistic.
Broadband video hurts: Broadband kills networks' success formula, driving profitable on-air viewership to profitless broadband viewership. It's pie-in-the-sky thinking to believe that broadband revenues will ever catch up. Since only a limited amount of ads can be included in online broadcasts, even the higher CPMs received per ad deliver nowhere close to the revenue per episode per viewer as the on-air model does. All the interactivity and engagement in the world will never offset this shortfall. As more programs move online and viewers can eventually watch these right on their TVs, the shift from on-air to online consumption will only accelerate, causing permanent erosion to the traditional economic formula.
So which is it - are networks helped or hurt by broadband? I think the answer is short-term it helps, but long-term it hurts. In the short-term, there is evidence that broadband expands audiences. For example, The Office's premiere last fall 9.7 million people tuned in, but another 2.7 million watched online.
Expanding viewership is great, but what happens to networks' revenues if next fall 7.7 million watch on-air and 4.7 million online? And 3 years from now, 5.7 million on-air and 6.7 million online? You can count on viewers to gravitate to the optimal viewing experience, and if online further improves, expect more eyeballs to shift. Again, since there are fewer ads online, the only way for total network revenues to keep pace are to show more ads online (see ABC's plan on that front), dramatically raise CPMs and/or dramatically raise viewership. My guess is that even the most optimal mix of these three will not deliver enough to offset on-air's revenue decline.
Broadband offers lots of complementary benefits to broadcasters to be sure. But NBCU's Jeff Zucker is absolutely right that the industry's number one challenge is the risk of turning "analog dollars into digital pennies." I can't say I see how that's to be avoided, unless networks go cold turkey, following CW, which recently pulled down streaming episodes of "Gossip Girl" to enhance on-air viewership. But I don't see that happening. Instead I think broadcast networks are going to have to adjust to fundamentally different economics in the future.
What do you think? Does broadband video help or hurt broadcasters? Post a comment!
Categories: Advertising, Broadcasters
-
Tremor, Adap.tv Introduce New Ad Platforms
The video ad management and networks space
, marked by competition among a group of privately-held companies, continues to evolve. In the last few weeks two key players, Tremor Media and Adap.tv have announced new solutions giving content providers more flexibility to optimally monetize their video inventory by easily accessing multiple ad sources. Given how essential the ad business is to broadband video's ultimate success, both products are welcome.Ad networks play an important role for content providers which either don't have their own ad sales team or as an augment for those that do. For the latter, ad networks help monetize their unsold inventory, particularly important during unexpected spikes in viewership. Traditionally content providers had two basic choices, each of which had disadvantages:
First, they could select one ad management/network partner. This kept things simple, but didn't necessarily optimize the inventory, because it was dependent on how well that one network's advertisers were matched to available inventory (resulting in either the inventory going unsold or users seeing the same irrelevant ad over and over again).
The second was to go with multiple ad networks. This improved optimization, but created multiple operational challenges trying to work with different ad managers, formats and reporting.
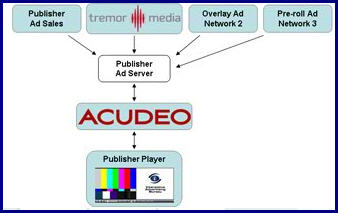
Both Tremor's new "Acudeo" platform, and Adap.tv's "OneSource" seek to resolve these problems by providing one management platform capable of handling multiple ad sources/ad networks across all ad inventory.
Jason Glickman, Tremor's CEO, explained to me that he's positioning Acudeo to do for video advertising what DoubleClick's DART did for banner advertising. Content providers can easily enable all kinds of complex ad rules around their inventory - the type of ad format to be used, their frequency and contextual targeting (with partner Digitalsmiths), their cueing and lastly, standardized reporting, so that ongoing campaign adjustments can be made. Acudeo aims to support all third party ad networks. Tremor prices Acudeo flexibly depending on whether the content provider also uses Tremor's ad network.
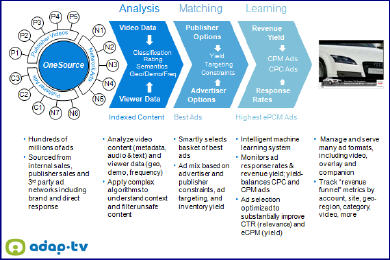
Adap.tv's recently introduced OneSource platform has the same goal of improving ad optimization with lower complexity. Amir Ashkenazi, Adap.tv's says OneSource differentiates itself by using Adap.tv's contextual advertising capabilities to optimize which third-party's ads to run. It does this by understanding the video content itself and then matching the optimal ads, factoring in the ad rules the content provider has preset. Amir believes that by doing so, it can raise the effective CPM delivered by 65%, from which OneSource's fee is deducted. OneSource has 40 third party ad networks currently integrated and also aims to support all ad sources.
Acudeo's and OneSource's potential is to bring more spending into the video category, which obviously would be extremely valuable. Last week, I expressed concern that with so many video content providers relying on advertising, a short-term squeeze is a real risk. Both Acudeo and OneSource are encouraging signs that the ad management and network businesses are continuing to mature, which will benefit everyone.
What do you think? Post a comment and let everyone know!
(Note: Both Tremor Media and Adap.tv are VideoNuze sponsors)
Categories: Advertising, Technology
Topics: Acudeo, Adap.TV, OneSource, Tremor Media
-
2009 Super Bowl Ads to Hit $3 Million, Broadband's Role Must Grow
The Wall Street Journal reported yesterday that NBC will announce next week that the starting price for a 30 second ad during the 2009 Super Bowl will cost $3 million, a 10% increase over 2008. For sure one thing this
 means to me: broadband video's role must grow in order to earn Super Bowl advertisers a return on these outsized rates.
As some of you know I've been writing about this topic for the last few years, even preceding the launch of VideoNuze. In Jan '06, in "The $10 Million Super Bowl Ad?" I argued that Super Bowl ad prices were heading nowhere but up given the historic opportunity to fuse the best of brand advertising with the best of online advertising.
I thought the linchpin would be brands recognizing that broadband video elements (e.g. larger campaign narratives, user contests, etc.) should precede and/or follow the game ad, creating a far larger engagement and ROI scenario. With more potential benefits, Super Bowl ad buying would be far less risky and therefore more advertisers would be compelled to buy, thus driving prices up.
While prices have risen, it's been more because audiences have continued fragmenting, making the Super Bowl truly a once-a-year advertising opportunity. NBC's willingness to raise prices by 10% over '08, in the face of a difficult U.S. economy is further testament to the big game's luster.
Back in '06 I forecasted that creative lightbulbs would be going off on Madison Avenue for how to capitalize on broadband's potential to add value. Sadly in the last 2 years this hasn't materialized. In Jan '08, in "My Rant About Super Bowl Ads" I lamented the fact that of the 52 game ads, only 5 (later revised to 6) ads had a broadband component. While the ads themselves were viewed for weeks after in online galleries, the stark reality was that tens of millions of dollars of client ad spending was being dramatically sub-optimized by not incorporating any broadband video elements.
It may be unfair of me to say, but I place the disproportionate share of the blame for this on the agencies behind the Super Bowl ads. They seem oblivious to how their clients' ad strategies must change to reflect broadband and online's importance.
So here's my message to brands considering a Super Bowl '09 ad buy: with 8 full months until game day, if your agency is not presenting you now with at least a half dozen compelling ideas for how to incorporate broadband elements into your Super Bowl ads, switch agencies now. I mean it. They are under-serving you. Find an agency that gets it, not one that is stuck in a time warp. The brands that will really score in the '09 game will have ads that reflect today's broadband realities.
Categories: Advertising, Brand Marketing, Sports
Topics: Super Bowl
-
Video Ad Networks Coverage Continued: SpotXchange, YuMe
As evidence of the market's bullishness on ad-supported video, video-focused ad networks continue to flourish. I recently spoke to CEO/co-founders of two of the larger ones, SpotXchange and YuMe to learn more about their respective differentiators.
SpotXchange CEO Mike Shehan explains that his company has focused on building a real-time auction model for publishers to offer inventory and advertisers/agencies to bid on it. The 2 main verticals
 SpotXchange is pursuing are local and casual games. Providing an easy on-ramp to video advertising is the key goal. Advertisers can load their campaigns, enter the marketplace, target by channel and/or region and determine how much they're willing to pay.
Though it's a fully self-service model, SpotXchange offers client service model as well for larger brand advertisers. Michael says there are now 300 publishers in the networks, reaching 50 million unique visitors per month. The company grew out of Booyah Networks, a search and interactive agency which has fully-funded its development.
Meanwhile, Jayant Kadambi, CEO of YuMe explains that the company spent the first 2 1/2 years from its
 founding in October '04 developing an ad-management platform that could handle various ad units and formats. In the absence of standards, Jayant believes this gives the company an edge in servicing advertisers and agencies that don't want to customize assets for various publisher sites' players. YuMe has built a network of 400+ publishers with 46 million uniques/month and a sweet spot of 750K-1 million video views/month and above (for a network total 150 million streams/mo).
Jayant says he's been pleasantly surprised at how much video content is monetizable, though he's not suggesting user-generated video will be monetized any time soon. YuMe's CPMs are in the $10-30 range. The company is now in the mode of building scale, which could involve marrying its ad management platform to others' networks using its "Adaptive Campaign Engine." In fact, one recent partnership that was announced to do this was with SpotXchange. YuMe has raised $16M from investors including Khosla Ventures, Accel Partners, BV Capital and DAG Ventures.
I'll have more on other video ad networks and how they fit into the larger broadband industry in the coming weeks.
Categories: Advertising, Technology
Topics: SpotXchange, YuMe
-
Insights Aplenty from How-to Video Category
One of the hottest corners of the broadband video market is the ad-supported "how-to" category. How-to lends itself well to video because, if a picture's worth a thousand words, a video is surely worth a million. Recognizing this, there's now a host of start-ups in this category which together have raised tens of millions of dollars. I wrote about some of this a couple months ago.
Several recent calls with industry participants got me to thinking the how-to category actually offers many valuable insights for all broadband industry participants. These fall into 3 key areas: content development, traffic acquisition and monetization.
1. Content: "Build Our Own" or "Offer a Superstore of Others' Videos"?
Players like Expert Village, 5Min, VideoJug and MonkeySee are pursuing the "build our own" video library approach, incenting individual "experts" to contribute to their sites. On the other hand, sites like WonderHowTo (WHT) and SuTree rely primarily on scouring user-generated video sites like YouTube, plus those above to aggregate the best videos available. With how-to being the ultimate "Long Tail" space,
 WHT's Stephen Chao told me in a recent briefing that trying to cover the infinite number of niches would be impossible. So to be comprehensive, relevant and high-quality, WHT curates what its crawlers return with a small in-house team and presents the cream of the crop to users, complete with a range of community-building features.
Here's one non-statistically significant example that illustrates the two approach's results: I did a search for "bbq steak video" on Expert Village, which bills itself as the "World's Largest How-to Video Site" and on WHT. EV returned 15 results, regrettably not one of which was relevant. WHT returned 357 results, and on the first page of 20 results alone, at least 12 looked relevant. These came from a wide variety of sources. Try doing a few searches and see what you find - my guess is your experience will be consistent with mine.
2. Traffic acquistion: Syndication or SEO?
All of these sites are ad-supported, so traffic is key. The sites with private libraries can syndicate to heavily-trafficked partners. Ordinarily, as a big syndication fan, I'd say that sounds like an advantageous traffic generating plan. But how-to may have a different traffic acquisition dynamic. It may well be that far more traffic will always come to these how-to video sites via searches at Google and other search sites, as compared with the sum of various syndication deals. That's because, absent a household brand-name in how-to, default consumer behavior may well be to simply type their how-to video query into Google.
If that's the case, then it will actually be those sites which have the most highly-optimized pages for all the
 niche videos that will gain greater traffic. Though I'm not an SEO expert, it seems to me that, taking my "bbq steak videos" example, WHT, with 357 related videos can optimize better than say EV with 15. And sure enough, when I ran the "bbq steak video" search on Google, right on the first page is a result from WHT, whereas nothing shows up for EV even after 5 pages. Bottom line: more relevant videos = more zero cost, Google-driven traffic.
3. Monetization: Video ads or Keyword-driven text/display ads?
Last but not least is monetization. How-to sites have lots of contextual ad potential. In my "bbq steak" example, any company that sells grills, steaks, sauces, etc, would love to advertise to me. It's tempting to believe that those with their own video libraries have more profit potential, because they can sell pre-roll or overlay ads, whereas a superstore site like WHT or SuTree cannot, because they're linking off to the source sites.
But consider this: how many of these potential advertisers will actually have video ads or the budget to create them? Unlike entertainment video, how-to, with its Long Tail character, seems to lend itself more to a low cost keyword ad approach which can be pursued by even the smallest advertiser. So say WHT or SuTree can build traffic in all those video niches and surround the video with keyword-driven text or display ads, all automated through a bidding system. Though yielding lower revenue per ad, my bet is that the total revenue for all ads with the keyword approach would be greater.
Summary
The how-to category is nascent and dynamic. I'm not suggesting for a second that it's a winner-take-all space or that all of the above are strictly "either/or." But I do believe the above analysis raises valuable points all industry participants should consider when developing their content, traffic and monetization strategies.
What do you think? Post a comment now!
Categories: Advertising, Indie Video, Startups, Strategy, Video Search
Topics: 5Min, Expert Village, MonkeySee, SuTree, VideoJug, WonderHowTo, YouTube
-
The Reality of Web Video Advertising Just Doesn't Seem to Add Up
Today's post is from TDG's Mugs Buckley, who discusses the confusing state of video advertising projections.
The Reality of Web Video Advertising Just Doesn't Seem to Add Up
by: Mugs Buckley, Contributing Analyst, The Diffusion Group
I used to think I was pretty good at math, but after trying to make sense of recent forecasts regarding web video advertising, I'm beginning to doubt my skills. Let it be known that I'm a big believer in the growth potential of the Internet video ad business; I'm simply struggling to follow the numbers that have been reported. Since no single analysis offers an "apples-to-apples" industry comparison, I thought I'd offer up some of the available forecasts and offer a few thoughts.
So here's where I'm stuck.
The estimates and forecasts for only video ads are all over the place. For example:
- eMarketer estimates that US marketers spent $775M in 2007 and will spend $1.3B in 2008 for online video streaming and in-page ads.
- Jupiter Research predicts that 2008 online video ads in the US will yield $768M.
- comScore reported that online viewers consumed 9.8B videos in January 2008 (down from December 2007's 10.1B) of which 3.4B were Google/YouTube videos.
- In a November 2007 Financial Times article, a leading media buyer for Starcom Media Group (who is well aware of her buys and rates) predicted that the 2007 market for "The Big Four" broadcast networks was likely to generate around $120M.
So here's where it gets a bit confusing.
- If we use the 3.4B monthly view Google/YouTube view estimate for January and run that out for a 12-month period, add some growth for fun, we come up with about 45B views for all of 2008.
- YouTube charges $15 CPMs for their in-video overlay ads (down from the initial $20 CPMs used during beta testing).
- If 100% of the 45B Google/YouTube videos were sold at $15 CPMs, that would yield revenue of $675M. But that assumes 100% inventory sold, which won't happen for a variety for reasons (in particular because YouTube only sells overly ads on their contracted partner deals, not user-generated content).
- According to Bear Stearns, YouTube is set to generate $22.6M in revenue for video ads, about 3.3% of the possible $675M at 100% inventory sold.
Hmmm. So if YouTube (at 34% of all web video consumed) could generate $22.6M in revenue in 2008, and the Big Four were running about $120M in 2007, how does one arrive at these impressive near-billion dollar predictions? Where else is this revenue coming from?
Let's not rule out operator error - I'll quickly admit that I may have misinterpreted how these numbers were derived and what they represent. That being said, however, there doesn't seem to be a rational way to reconcile these disparate estimates. Can anyone out there help to square these numbers? Is it simply a matter of under- or over-reporting? Are the measurement systems currently in place so poor and mutually exclusive in methodology that they necessarily offer conflicting estimates?
Something just isn't adding up. Yes, this may seem to be a bit nit-picky on my part; the rambling of an analyst with too much time on her hands. Then again, without accurate revenue and usage estimates, it is impossible to know the real value of any form of advertising, much less an emerging model such as web-based video advertising.
Please let us know what you think!
Categories: Advertising
Topics: comScore, eMarketer, Jupiter Research, The Diffusion Group, YouTube
-
Why Adobe Media Player Could Matter
Yesterday brought the public release of Adobe Media Player 1.0, first announced almost a year ago. AMP enters a very crowded space of other media players including its own Flash player, plus Windows Media Player, RealPlayer, QuickTime, SilverLight and others.
At a time when the broadband video industry in general and mainstream users in particular crave
 standardization and simplicity, can another media player, with a "walled garden" content strategy to boot, add new value? While it's awfully tempting to say "no," I think there are reasons why AMP could well matter, subject to how well Adobe delivers on its vision. Here's why:
AMP offers 2 things that, in my opinion, the market still needs. First, a widely used downloadable app that specializes in delivering on FREE video content. Before some of you jump up and say, "Will, what about iTunes?" keep in mind that iTunes offers primarily a PAID video catalog (though to be sure there are some free video podcasts). Second, and related, AMP' provides a download environment in which advertising can be properly inserted, measured and reported on.
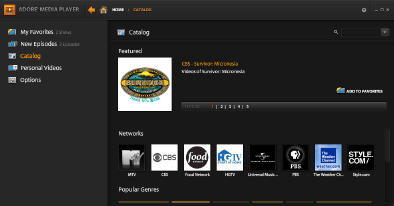
These are important because together they open up an entirely new consumer use case for broadband video: offline, free, ad-supported viewing. I've been saying for a while that an odd dichotomy has taken root in the broadband industry, particularly for network programs: users can get either free, ad-supported streamed video at lots of places (provided they're online) OR they can get paid, downloaded video (iTunes model) which allows offline viewing. But this has meant that someone who wants to watch a show offline, but isn't willing to pay for the pleasure of doing so is out of luck (one exception is NBC Direct). Having media stored locally in AMP would allow the offline, free use case I'm describing. This would open up a boatload of premium ad inventory that advertisers savor.
If that's AMP's opportunity, then the question is how well are they executing on it? Though it's never fair to judge a version 1.0 on its first day, my experience with AMP shows there's room for improvement. First is the currently thin content selection that needs to be massively built out to be appealing and competitive. Second is an inconsistent user experience in which some shows are downloadable, yet many are not (e.g. CSI, Hawaii Five-O, Melrose Place). Third are getting the basics right. In my case, when I did download some episodes successfully (blip.tv's "DadLabs" and "Goodnight Burbank") they didn't show up in my download section at all. Ugh. I'm hopeful that Adobe will be able to address all of these.
On the ad side, I think there will be plenty of enthusiasm from ad technology firms to integrate with AMP as Adobe proves it can drive millions of AMP downloads (in fact Kiptronic announced its integration yesterday and other will surely follow). Plus, advertisers should be expected to get on board.
It should be noted however, that even for a mighty brand like Adobe, winning the hearts and minds of users to download and use AMP isn't a trivial undertaking. I have some personal experience with this from my early days consulting at Maven Networks, which offered an eerily similar download app as AMP when the company started up. Though that was in the Mesozoic broadband era of 2003 and Maven was an unknown entity, the company never got much traction with its download app and eventually transitioned over to a streaming model. Since then I've come to believe that premium content must drive the download process, not vice-versa. One successful example of this is ABC.com using its shows to drive millions of downloads of the Move Networks player.
Net, net, AMP is a timely product that could well matter. How well Adobe executes on its vision will determine to what extent it does.
Categories: Advertising, Broadcasters, Downloads, Technology
Topics: ABC, Adobe, Adobe Media Player, Kiptronic, Maven Networks
-
What Media Planners Think of Online Video Advertising
Continuing VideoNuze's series of posts about the online video advertising industry, last week I spoke to Alistair Goodman, who's the VP of Strategic Marketing at Exponential Interactive, a media services company with hundreds of advertising clients and publishers in the digital media space.
Exponential recently released the results of a survey of 100 ad agency media planners' perceptions of online video advertising. To the best of my knowledge, the survey, "The Trials and Tribulations of Online Video
 Advertising," is the first one focused on what the people actually responsible for spending money in this new medium think (the survey is evenly split between those who have bought and those considering buying). Most prior research has focused on users' or publishers' attitudes. The research confirms many things I hear each day, and also reveals some new insights on the market.
I'm very pleased to offer a complimentary download of a subset of the Exponential's slides exclusively here at VideoNuze. If your business is reliant on video advertising, I highly suggest reviewing them. If you have questions or want to receive the full deck, there is contact info on the last slide.
The top 2 issues for planners who have actually bought video ads are operationally-oriented: "smooth delivery" and "detailed reporting." As Alistair described it, these factors (and others cited) confirm the complexity of executing a campaign at scale. The complexity results from lack of standards, multiple players/formats, fragmentation of viewership and non-standard metrics. None of this is unexpected in a market as nascent as online video; the challenge is addressing and resolving these quickly for online video to reach its full potential.
In the past I've mentioned repeatedly that monetization is the number 1 priority for both established and early stage video content providers. This is an urgent issue because lots of energy and money is being invested in creating online video content, but the financial returns are not there yet. These payoffs need to materialize if the enthusiasm around this new medium is to be sustained.
Click here to download the Exponential slides.
(Note: I have created a new section in VideoNuze to offer all downloads of all relevant market research. If you have complimentary industry data please contact me and I'll add it to the page.)
Categories: Advertising
Topics: Exponential Interactive, Tribal Fusion
-
BobVila.com Illustrates Opportunities, Challenges for 'Mid-Tail' Content Providers
I frequently hear the same segmentation framework used to describe today's broadband video providers. Between the small group of premium providers (e.g. broadcasters) and user-generated sites (e.g. YouTube), lie the so-called "mid-tail" (in "Long Tail" terminology) providers such as newspapers, magazines, online publishers, and indie producers. BobVila.com is a perfect example of a mid-tail provider. Dan Newberry, the company's VP Advertising and Marketing, who I recently spoke with, discussed these opportunities and challenges.
Some of you may know that Bob Vila hosted a hugely popular PBS program from 1979-1989 called "This Old House." He then set up his own production company and produced 2 syndicated shows, "Bob Vila's Home Again" and "Bob Vila." At the end of the latter's run, he decided to shift his focus exclusively to online, to his BobVila.com web site which had been growing since the Internet's earliest days.
As Dan explains, one of the motivations (in addition to Bob Vila's personal reasons) was the improving climate for online advertising in general and video advertising in particular. The economics of creating quality programming for TV vs. for online, plus the CPMs available online, made the case for shifting to online only. The site now generates 1.7 million unique visitors/mo and 600K-700K video streams/mo, with 1,700 video clips available.
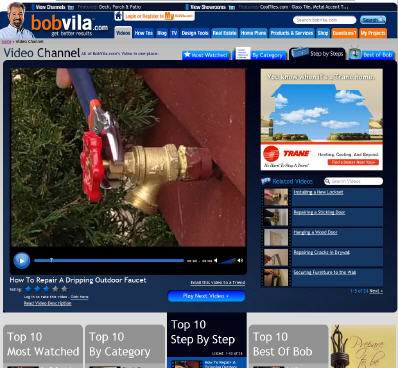
Responding to its audience's desires, BobVila.com now produces 5-7 minute step-by-step how-to videos for the site. It has created about 100 since June '07. While broadband enables this new model, Dan is clear about the challenges.
First and foremost is making the financial equation work. This involves producing videos on a disciplined budget and maximizing ROI. Their target cost to produce each video is $4-5K, which requires a different approach than with TV production. Given current viewership and CPMs, Dan calculates that break-even on an individual video is projected at 24 months.
To monetize their video, BobVila.com uses an internal sales team and is able to generate pre-and mid-roll CPMs in the $25-40 range. If there's unsold inventory then it uses a network to sell it, usually garnering $7-12 CPM. In addition, it also selectively uses overlay ads from Google AdSense. Setting the ad strategy to maximize revenue is key. As Dan noted, staffing and managing an internal sales team in this highly competitive environment is a challenge that startup sites need to fully recognize.
Increasing video views is another key challenge. Acknowledging the limitations of search and on-site generated traffic, BobVila.com is ramping up an aggressive syndication effort. While offering lots of upside, Dan explains that this syndication will present new operational and financial complexities such as ensuring BobVila.com gets paid, content is distributed where and when it should be, enforcing various rights issues, etc. Dan pointed out the importance of having a solid technology partner (BobVila.com used PermissionTV) which enables syndication, flexible players and content management.
When you put it all together, it's clear that while broadband offers mid-tail providers like BobVila.com huge new opportunities, it also creates new challenges and responsibilities that many content providers have not typically dealt with. Surmounting these will determine how well these mid-tail providers ultimately fare.
Categories: Advertising, Indie Video
Topics: BobVila.com
Posts for 'Advertising'
Connect with VideoNuze
Exclusive News Roundup
- Jimmy Kimmel is moving a Senate candidate interview to YouTube to sidestep FCC pressure Quartz
- Universal Music is launching an AI music platform with ElevenLabs The Verge
- Katzenberg and Ex-Sora Head Bill Peebles Launch AI Video Startup for Filmmakers AI Weekly
- Suno Launches New AI Model Trained on Licensed WMG, BMG Tracks The Hollywood Reporter
- Justice Department to take a closer look at Fox’s $22 billion Roku deal Semafor
- Congress Begins Drafting 20% Federal Film Incentive With Trump’s Blessing Variety