-
4 Items Worth Noting from the Week of August 31st
Following are 4 news items worth noting from the week of August 31st:
1. Nielsen "Three Screen Report" shows no TV viewing erosion - I was intrigued by Nielsen's new data out this week that showed no erosion in TV viewership year over year. In Q2 '08 TV usage was 139 hours/mo. In Q2 '09 it actually ticked up a bit to 141 hours 3 minutes/mo. Nielsen shows an almost 50% increase in time spent watching video on the Internet, from 2 hours 12 minutes in Q2 '08 to 3 hours 11 minutes in Q2 '09 (it's worth noting that recently comScore pegged online video usage at a far higher level of 8.3 hours/mo raising the question of how to reconcile the two firms' methodologies).
I find it slightly amazing that we still aren't seeing any drop off in TV viewership. Are people really able to expand their media behavior to accommodate all this? Are they multi-tasking more? Is the data incorrect? Who knows. I for one believe that it's practically inevitable that TV viewership numbers are going to come down at some point. We'll see.
2. DivX acquires AnySource - Though relatively small at about $15M, this week's acquisition by DivX of AnySource Media is important and further proof of the jostling for position underway in the "broadband video-to-the-TV" convergence battle (see this week's "First Intel-Powered Convergence Device Being Unveiled in Europe" for more). I wrote about AnySource earlier this year, noting that its "Internet Video Navigator" looked like a content-friendly approach that would be highly beneficial to CE companies launching Internet-enabled TVs. I'm guessing that DivX will seek to license IVN to CE companies as part of a DivX bundle, moving AnySource away from its current ad-based model. With the IBC show starting late next week, I'm anticipating a number of convergence-oriented announcements.
3. iPhone usage swamps AT&T's wireless network - The NY Times carried a great story this week about the frustration some AT&T subscribers are experiencing these days, as data-centric iPhone usage crushes AT&T's network (video is no doubt the biggest culprit). This was entirely predictable and now AT&T is scrambling to upgrade its network to keep up with demand. But with upgrades not planned to be completed until next year, further pain can be expected. I've been enthusiastic about both live and on-demand video applications on the iPhone (and other smartphones as well), but I'm sobered by the reality that these mobile video apps will be for naught if the underlying networks can't handle them.
4. Another great Netflix streaming experience for me, this time in Quechee VT courtesy of Verizon Wireless - Speaking of taxing the network, I was a prime offender of Verizon's wireless network last weekend. While in Quechee, VT (a pretty remote town about 130 miles from Boston) for a friend's wedding, I tethered my Blackberry during downtime and streamed "The Shawshank Redemption" (the best movie ever made) to my PC using Netflix's Watch Instantly. I'm happy to report that it came through without a single hiccup. Beautiful full-screen video quality, audio and video in synch, and totally responsive fast-forwarding and rewinding. I've been very bullish on Netflix's Watch Instantly, and this experience made me even more so.
Per the AT&T issue above, it's quite possible that occupants of neighboring rooms in the inn who were trying to make calls on their Verizon phones while I was watching weren't able to do so. But hey, that was their problem, not mine!
Enjoy the weekend (especially if you're in the U.S. and have Monday off too)!
Categories: Aggregators, Deals & Financings, Devices, Mobile Video
Topics: AnySource, Apple, AT&T, comScore, DivX, Intel, iPhone, Netflix, Nielsen, Verizon Wireless
-
Interview with boxee Investors Bijan Sabet and Neil Sequeira
When boxee announced it raised a $6M second round last week it caught my attention for two reasons. First, it was further evidence that broadband video-related companies are continuing to raise money right through the current economic meltdown (industry companies raised at least $64M in Q2 '09, $75M in Q1 '09 and $78M in Q4 '08).
Second, and more noteworthy to me was how much industry experience and insight now backs boxee. The new lead investor in the round was Boston venture firm General Catalyst Partners (joining prior investors Spark Capital and Union Square Ventures), whose portfolio includes broadband video companies like Brightcove, DECA, EveryZing, Maven Networks (acquired by Yahoo), ScanScout, ViTrue and Visible Measures.
Spark also has many investments in the industry, including 5Min, Adap.tv, EQAL, KickApps, Next New Networks, thePlatform (acquired by Comcast) and Veoh. And Union Square is one of the most active firms in the online media/advertising industry with stakes in MeetUp, OddCast, Twitter (with Spark), Tacoda (acquired by AOL) and others.
Beyond the firms themselves are the individuals helping steer boxee. Joining its board from GC is Neil
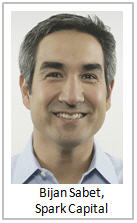
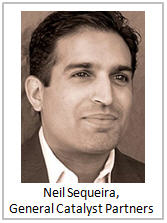 Sequeira, a veteran of the cable industry, who was most recently Managing Director, Technology of AOL Time Warner Ventures. Already on the board is Spark's Bijan Sabet who knows the cable/satellite ecosystem equally well, having done stints at Moxi, WebTV and Apple and Union Square's Fred Wilson, who is deeply immersed in online media and writes a hugely popular blog.
I corralled Neil and Bijan (two old friends) for a phone interview late last week to explain boxee's future and where it fits into the current video ecosystem. Following is an edited transcript.
VideoNuze: What attracted you to invest in boxee?
Neil Sequeira: Three things. The boxee team, the market opportunity and our ability to be a great partner. We think boxee has the potential to be the next generation "Firefox for media," a widely- used consumer platform. That's incredibly exciting to us.
Bijan Sabet: We've been involved with boxee for a while now, and we're convinced the time is right for something like this. boxee has the right ingredients: it is open source and includes social media capabilities, an app store and a huge community of users/developers.
VideoNuze: boxee has gained a loyal following, but it doesn't have a business model yet. What do you see as boxee's business model and it what time frame must it develop it in order to succeed?
BS: boxee's still a very young company, but we have a number of ideas around business models. But the key is patience. The company has a very low burn rate, with around 16 people or so , most of whom are in Israel. The focus for now is building the product and the user base. And the company's been very successful doing that. Last year boxee had 10,000 users, now it has 600,000.
NS: It also has a very excited developer community. But I agree - patience is needed here. Too often companies can get themselves focused to early on a specific business model, which then constrains them. With the new funding, box has room to see how things evolve.
VideoNuze: Hulu recently told boxee to remove its content. What do you think boxee needs to do to win Hulu (and others) onto its platform?
NS: At a high level boxee we believe boxee is an incredible friend to content providers, and we want to work with everyone. We're big believers that consumers want access to everything and that's where the market will go over time.
 BS: All of us are Hulu fans and of course would love to have Hulu on boxee. But each content provider has its own business model, and has to decide what works best for them. boxee will continue to be a content provider-friendly platform, where different business models can be used and different technologies integrated. We think that's powerful.
VideoNuze: How should established video service providers (i.e. cable/satellite/telco) regard boxee - as friend, foe, or something else?
NS: We want boxee to be regarded as friend and we think boxee can add a lot of value to the ecosystem. Consider for example, the case of TiVo. Early on it looked like a foe. But now see how Comcast is integrating TiVo into its set-top boxes and driving incremental revenue. boxee brings great search, apps and context to the broadband viewing experience. All that will drive usage of broadband Internet connections, which in turn helps "fill the pipe" making cable and telco Internet access services that much more valuable to users - and to their providers.
BS: Agreed. We believe that in an IP world, these things aren't either/or, mutually exclusive. Again look at Comcast, which has great assets like Fancast, and is now working on entitlements with TV Everywhere. boxee can help drive more value from them. This is especially true for certain user segments, like new college grads, for whom the Internet is now far more important than is traditional TV. The point is traditional service providers need to figure out how to delight a variety of user segments. We believe boxee can help.
VideoNuze: You guys and your firms have deep relationships in the cable/satellite/telco industries. How are those folks reacting to boxee?
NS: People in the ecosystem are taking a "wait-and-see" approach. There's a certain amount of fascination, and though we don't see any impending deals, Avner (Ronen, boxee's founder/CEO) has multiple conversations ongoing with the industry.
VideoNuze: Who are boxee's primary competitors?
BS: What Apple and Microsoft are doing is most competitive, though their approaches include both hardware and software. We think of boxee like Android (Google's mobile OS), sort of the "inside-out" version of Apple TV. And we believe convergence device/hardware providers want alternatives.
VideoNuze: How about Roku?
NS: We believe Roku should be partners with boxee. Hardware companies have core competencies and typically those don't include open source media platforms. So boxee can help devices like Roku be even better. We'll have a number of device deals to announce soon.
VideoNuze: A lot has been written about "over-the-top" services. Are they starting to succeed, and if so, what must happen for them to gain further success?
NS: Well, yes, when we look at what Netflix and others are doing already, we do believe over-the-top services are starting to succeed. And we think this isn't necessarily a bad thing for cable operators for example. That's because the video business has had margin compression due to rising programming costs, whereas broadband Internet service has been incredibly profitable for them.
Consider that that cable operators didn't offer DVR or voice services just 10-11 years ago, but now they are a significant driver of ARPU (average revenue per unit). There's a lot more that cable operators can derive from broadband services than they currently are, considering the IP connection is now - for many - the most important connection they have. Content providers know this and are looking for more, not fewer, ways to distribute their content.
BS: Agreed, look at an example like CNBC, whose ratings are down something like 30% year-over-year. What's causing this? Is there demo changing? Is the web providing alternatives? Some of both? The point is content providers need to figure out how to control their destiny. That doesn't mean they have to give their stuff away for free. But it does mean they need to figure out how to distribute as effectively as possible. We want to help them do that. You can't go backwards here. Broadband is too interesting and too important to too many people.
VideoNuze: Thanks guys.
Categories: Cable TV Operators, Deals & Financings, Devices, Satellite, Telcos
Topics: Boxee, General Catalyst, Spark Capital, Union Square Ventures
-
4 Items Worth Noting from the Week of August 3rd
Following are 4 items worth noting from the week of August 3rd:
1. Research, research, research - For some unknown reason, there was a flurry online video-related research and forecasts released this week. In no particular order:
eMarketer was out with a new forecast indicating 188 million online video viewers in the U.S. in 2013.
Veronis Suhler released its forecast of 2009-2013 communications industry spending, showing advertising shrinking as a percentage of total spending.
PWC's UK office released its 2009-2013 forecast, which also anticipates declines in advertising.
CBS's research head David Poltrack used detailed data to explain the company's online video strategy and buttress its argument that in a TV Everywhere world, it should be compensated for its content (slides are here, via PaidContent).
Ipsos found that Americans streamed a record amount of TV programs and movies, doubling their consumption from Sept '08 to July '09.
Yahoo and a group of research partners released data finding that 70% of online video consumption happens throughout the day and night, as opposed to traditional TV viewing which is concentrated in the prime-time window.
Last but not least, TDG released excerpts of its research on "over-the-top" video services, available for download at VideoNuze.
2. Unicorn Media launches, hires ex-Move Networks executive David Rice - It will be hard for some to believe there's room for yet another white label video publishing and management platform, but startup Unicorn Media is going to try elbowing its way into the crowded space, with a specific focus on large media companies. I spoke with Unicorn's executive team this week, led by Bill Rinehart, who was the founding CEO of Limelight.
Unicorn is positioning itself as the first "enterprise-grade" solution, staking out key differentiators such as enhanced analytics/reporting, faster/easier transcoding, improved APIs for content ingest/management and more flexible monetization/ad queuing. I have not yet seen a demo, but I'm intrigued by what I heard. The company has raised $5M to date from executives/angels and has a staff of 25. David Rice, formerly Move's VP of Marketing has come on board as Chief Strategy Officer. Given the team's industry expertise and relationships, this could be a company to watch.
3. Google acquires On2 Technologies and other encoding-related news - The blogosphere was in a flurry about Google's $106M acquisition of video compression provider On2 Technologies this week. Speculation flew about Google open-sourcing On2 new VP8 codec, which could potentially force a new standard to emerge as a challenge to H.264, today's leading codec. This is important stuff, though a little further down the stack than I usually focus, so I refer you to Dan Rayburn's analysis of the deal's implications, which is the best I've seen.
There was other news in the emerging cloud-based encoding/transcoding/delivery market this week, as Encoding.com announced a new premium service with tighter service level agreements (4 minute max wait time and 50 Gbyte/hour/customer throughput). Encoding.com's Gregg Heil and Jeff Malkin explained the company is using the new SLAs to move upmarket to service tier 1 and 2 media companies. Separate, Encoding.com's competitor mPoint's CEO Chiranjeev Bordoloi told me they're now on a $3M annualized revenue run rate as cloud-based alternatives continue to gain acceptance.
4. Don't try this at home - On a lighter note, there's been no shortage of knuckle-head stunt videos we've all seen online, but this one is near the top of my personal favorite list. Do NOT try replicating this over the weekend!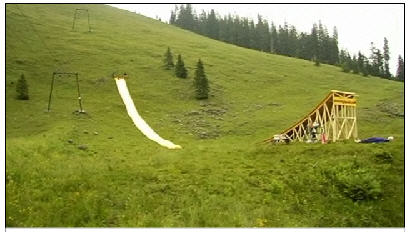
Categories: Deals & Financings, Technology
Topics: CBS, eMarketer, Google, Ipsos, ON2, PWC, TDG, Unicorn Media, Veronis Suhler, Yahoo
-
Video Syndicator 5Min Raises $7.5 Million Series B Round
5Min, a video syndication company specializing in "how-to" content, is announcing this morning that it has raised a $7.5 million series B round, led by new investor Globespan Capital Partners with participation from prior investor Spark Capital. The new round comes on top of the $5 million first round the company raised in January '08. I spoke with CEO Ran Harnevo yesterday to learn more about the company's progress.
5Min, which I last wrote about in Dec. '08, is a textbook Syndicated Video Economy company. As Ran
 explained, its key value proposition is an automated, comprehensive solution for sites seeking to incorporate high-quality relevant video that also offers content providers viewership reach and awareness beyond their own destination sites. There is no cost to either distributors or content providers to participate and resulting ad revenues are split among the parties.
The model is enabled by 5Min's VideoSeed syndication platform, which matches video from 5Min's 100,000+ title catalog to pages that its distribution network's sites specify. The matching is based on the video's metadata which 5Min has assigned and a semantic understanding of the pages themselves. 5Min's video player is embedded on these pages, providing content and ads. The network now consists of hundreds of horizontal (e.g. Answers.com, Wikia, etc.) and vertical sites that reach over 200 million unique visitors/mp generating 14 million unique viewers/mo. This is in addition to the 3.5 million unique visitors to its 5Min.com site. Ran wouldn't specify how many actual video views the network is driving, but said it's in the "tens of millions per month."
5Min focuses on key categories in lifestyle, knowledge and instructional and has built critical mass important for advertisers seeking to contextually target these viewers. 5Min has its own sales team and also uses 3rd party ad networks. Primary units are pre-rolls and overlays. Ran says the company has sold out 100% of its inventory, but would only say CPMs are on the "high end of the market."
5Min continues to aggressively grow its content library, but without producing any of its own content. Ran believes strongly that there's plenty of great content out there already, the challenge producers have is getting it more widely distributed, viewed and monetized (all the things 5Min focuses on).
Historically the company has sourced mainly from DVDs, small-to-medium sized video producers and semi-professionals (all with agreements). 5Min is also starting to offer branded content from partners like UGO Entertainment, Motor Trend, Ford Models, Kiplinger's and others. Ran also alluded to upcoming deals with tier 1 video brands. The how-to category itself is chock full of competitors like Demand Media, Howcast and VideoJug that are producing their own video, but at this point the only how-to specific provider 5Min has a deal with is MonkeySee.com.
I'm not surprised by 5Min's success. It is playing to many of the most important trends in the online video space I've written about repeatedly: fragmentation of audiences, the importance of search and SEO for discovery, higher CPMs through targeted advertising, technology to drive distribution scale and the superior value to consumers in certain categories (especially how-to) of video-based content over traditional text-based alternatives. As more and more sites recognize they need video to stay competitive, but that producing it themselves is an expensive and uneconomic proposition, syndicators like 5Min will enjoy ongoing success.
What do you think? Post a comment now.
Categories: Deals & Financings, Syndicated Video Economy
Topics: 5Min, Globespan Capital Partners, Spark Capital
-
Is My Prediction That Microsoft Will Acquire Netflix Going to Come True?
Amid the chatter over the past few days about Amazon possibly buying Netflix, Kara Swisher at All Things Digital today instead suggested that Microsoft would make a better Netflix acquirer. Her sentiments echoed my Dec '08 prediction that Microsoft would acquire Netflix at some point in '09. It was admittedly a "long ball" call on my part (especially since I had zero inside dope), but one which actually makes even more sense 7 months later.
Why? Because Comcast and the cable industry's aggressive new TV Everywhere/On Demand Online initiatives make Netflix more valuable than ever for any company looking to offer a subscription-based,
 broadband-delivered video service. Outside the cable/satellite/telco industries themselves, Netflix - with its 10 million+ current DVD-by-mail subscribers - is the only serious subscription video provider. Its recent stellar performance shows the durability of its model even in the face of the ongoing recession. And it continues to build out its streaming service with various device partners (including notably Xbox 360).
If Comcast succeeds with On Demand Online (and since the technical trial hasn't even begun yet, that's still a big "if"), and other cable operators quickly follow suit, the broadband video industry is poised for a fundamental shift away from ad-only business models to hybrid models where subscriptions are key. Any current or aspiring premium video provider that does not have an established subscription approach is going to be disadvantaged in its access to high-quality programming and ongoing product development resources. CBS's addition to Comcast's trial shows that even broadcasters are beginning to position themselves in the subscription mix.
My full rationale for why Netflix is so appealing for Microsoft is laid out in the Dec post, so I won't restate it here. Of course nobody outside the companies involved knows if any of the M&A chatter is for real. But if it is, my bet is still that Microsoft is the acquirer to watch, not Amazon. I suspect we'll see other analysts making a similar case if things heat up.
What do you think? Post a comment now.
Categories: Aggregators, Deals & Financings
Topics: Amazon, Comcast, Microsoft, Netflix
-
Catching Up on Last Week's Industry News
I'm back in the saddle after an amazing 10 day trip to Israel with my family. On the assumption that I wasn't the only one who's been out of the office around the recent July 4th holiday, I've collected a batch of industry news links below so you can quickly get caught up (caveat, I'm sure I've missed some). Daily publication of VideoNuze begins again today.
Hulu plans September bow in U.K.
Rise of Web Video, Beyond 2-Minute Clips
Nielsen Online: Kids Flocking to the Web
Amid Upfronts, Brands Experiment Online
Clippz Launches Mobile Channel for White House Videos
Prepare Yourself for iPod Video
Study: Web Video "Protail" As Entertaining As TV
In-Stat: 15% of Video Downloads are Legal
Kazaa still kicking, bringing HD video to the Pre?
Office Depot's Circuitous Route: Takes "Circular" Online, Launches "Specials" on Hulu
Upload Videos From Your iPhone to Facebook Right Now with VideoUp
Some Claims in YouTube lawsuit dismissed
Concurrent, Clearleap Team on VOD, Advanced Ads
Generating CG Video Submissions
MJ Funeral Drives Live Video Views Online
Why Hulu Succeeded as Other Video Sites Failed
Invodo Secures Series B Funding
Comcast, USOC Eye Dedicated Olympic Service in 2010
Consumer Groups Push FTC For Broader Broadband Oversight
Crackle to Roll Out "Peacock" Promotion
Earlier Tests Hot Trend with "Kideos" Launch
Mobile entertainment seeking players, payment
Netflix Streams Into Sony Bravia HDTVs
Akamai Announces First Quarter 2009 State of the Internet Report
Starz to Join Comcast's On-Demand Online Test
For ManiaTV, a Second Attempt to be the Next Viacom
Feeling Tweety in "Web Side Story"
Most Online Videos Found Via Blogs, Industry Report
Categories: Advertising, Aggregators, Broadcasters, Cable Networks, Cable TV Operators, CDNs, Deals & Financings, Devices, Indie Video, International, Mobile Video, Technology, UGC
Topics: ABC, C, Clearleap, Clippz, Comcast, Concurrent, Hulu, In-Stat, Invodo, iPod, Kazaa, Nielsen, Office Depot, Qik, VideoUp, YouTube
-
VideoNuze Report Podcast #23 - July 2, 2009
Below is the 23rd edition of the VideoNuze Report podcast, for July 2, 2009.
This week Daisy shares additional information about ESPN's Ad Lab for emerging media. The Ad Lab, which was first disclosed by ESPN last year, is intended to various ad formats in the ESPN video player. It is one of many different tests and research projects in the market. As Daisy and I say, everyone's trying to learn how best to monetize the nascent online video; this creates a lot of valuable data, which market participants then need to parse through to fully understand.
I get into further details on my post yesterday, "Video Companies Raised $64M in Q2 '09, Notching Another Stellar Quarter." Despite the recession and the slowdown in venture capital investments, at least 26 industry companies have raised at least $219M over the last 3 quarters, which is impressive by any measure. Still, it hasn't been easy, and one indicator of what investors prefer is that not one of the 26 investments is in a content provider or video aggregator.
Click here to listen to the podcast (14 minutes, 24 seconds)
(Note, with vacations planned, our next podcast will be July 24th)
Click here for previous podcasts
The VideoNuze Report is available in iTunes...subscribe today!
Categories: Advertising, Cable Networks, Deals & Financings
-
Video Companies Raised $64M in Q2 '09, Notching Another Stellar Quarter
In Q2 '09, 9 broadband and mobile video-oriented companies raised at least $64M, notching another stellar quarter. Here's what I tracked for the quarter (if I missed anything, please drop me a note). I've identified when new investors participated:
- TubeMogul (3M) 4/1 - Trinity Ventures
- ScanScout ($5.1M) 4/13
- FreeWheel ($12M) 4/30 - Foundation Capital
- Azuki Systems ($6M) 5/5
- EveryZing ($8.25M) 5/11 - Peacock Equity
- Grab Networks ($12M) 6/2
- beeTV ($8M) 6/3 - Innogest
-
YuMe ($2.9M) 6/12
-
Nokeena Networks ($6.5M) 6/25 - Mayfield
(Note that I've included beeTV, which offers a cross-platform TV recommendation system, so isn't a pure broadband or mobile video company. On the other hand, one might argue that Sugar's $16M round should also be included, since the company simultaneously announced the acquisition of video-oriented Shopflick.com and launch of Sugar Digital Entertainment. However, I haven't counted it since Sugar's more of a pure blog network.)
Excluding Sugar, the $64M comes on the heels of approximately $75M raised in Q1 '09 and over $80M raised in Q4 '08. That means over the last 3 quarters - arguably the heart of the current recession - at least 26 companies have raised a total of $219M. To be sure, everyone I've spoken to has told me these rounds have been hard work to raise, but these companies' successes demonstrate the appeal of the broadband video sector to investors and their anticipation for continued rapid growth.
One thing worth noting is that of the 26 companies, not a single one is a video producer itself, or even an aggregator of video. There has been a significant shift in investor sentiment away from content and towards the platforms and tools required to power video. While that's lamentable, it's also completely understandable. The bruising advertising environment, combined with ongoing business model uncertainty and the death of certain independent producers (e.g. 60Frames, Ripe Digital, etc.) has frozen new content investments. Aggregators aren't faring much better. Just today it was reported that Joost CEO Mike Volpi is stepping aside, as the company tries to relaunch itself as a technology provider. Veoh also restructured during the quarter, shedding half its staff and replacing CEO Steve Mitgang (in addition, just yesterday a VideoNuze reader emailed me saying he can't seem to find a working phone number for the company).
Couple all this with the rise of Hulu, the dominance of YouTube, the entry of cable operators and networks with TV Everywhere, and it's clear that on the content side at least, incumbents and earlier market entrants are ascendant, while more recent entrants and startups are having a tough time surviving the downturn. I anticipate this will continue to be the trend, at least until the economy rebounds.
What do you think? Post a comment now.
Categories: Deals & Financings
Topics: Azuki, beeTV, EveryZing, FreeWheel, Grab Networks, Nokeena, ScanScout, TubeMogul, YuMe
-
R.I.P. Maven Networks
Well, it looks as though it's official: as reported by TechCrunch and others, Yahoo is discontinuing Maven Networks's third party video publishing activities though Yahoo's statement says it will use Maven technology for internal video efforts. As I've mentioned periodically, I was an early consultant to Maven, which was a pioneer in the video platform space.
Way back then (!) in 2003 most people in the media business still had a difficult time imagining why broadband video was so strategic and game-changing. Maven's team did a lot of the early spadework in evangelizing broadband's potential and building market momentum. Its reward was being acquired for $160M by Yahoo in February, 2008 in what I believe is still the largest pure play broadband deal.
However, the Yahoo acquisition was never a perfect strategic fit, even before factoring in the well-documented chaotic mess that Yahoo has become in recent years. The problem was that Yahoo is a media company, deriving the majority of its revenue from advertising. On the other hand, Maven was a technology/products company (though some in the industry always questioned the true proprietary value of Maven's technology). The most strategic deal for Maven would have been with a larger technology/products company, where it would have become part of broader suite of video products and services. Yahoo was never really well-suited to support Maven's third party video customers (and in reality it hasn't for a while now), and with all its other troubles, this move was widely expected.
For Maven's founders and investors, the company's acquisition marked a successful exit that others in the industry envy, particularly in this crummy M&A market. Still, the Yahoo-Maven deal is yet another example that when selling a company, price isn't the sole criteria for longer-term success.
Categories: Deals & Financings, Portals, Technology
-
Unveiling Move Networks's New Strategy
Move Networks, the well-funded Internet television technology company which has been virtually silent for the last 60 days since acquiring Inuk Networks and bumping former CEO John Edwards to Executive Chairman, is pursuing a major repositioning. Earlier this week I met with Marcus Liassides, Inuk's former CEO and founder who joined Move's management team, who previewed the company's new strategy to be a wholesale provider of IPTV video services delivered over open broadband networks.
Broadband video industry participants know Move best for its proprietary adaptive bit rate (ABR) technology and player, which power super-high quality live and on-demand video streams for broadcasters
 like ABC and Fox. Move gained a lot of attention by raising over $67M, including a $46M Series C round in April '08 from blue chip investors.
Despite all this, Marcus explained that coming into 2009 Move had at least 3 significant problems, symbolic of how fluid the broadband video market remains.
First, its core business of charging content providers in the range of $.30/GB of video delivered was being pressured by the fact that advertising-only business models couldn't support this pricing. Content providers loved Move's quality; they just couldn't afford it, particularly given the alternative of plunging CDN delivery rates.
Second, Move's pricing and business model were being challenged by both Microsoft and Adobe entering the market with ABR streaming features of their own (I wrote about this here). But because both were enabled on the server side (IIS and FMS respectively), the cost of ABR moved from content providers to CDNs, who might or might not choose to charge extra for these features. Either way, Move's direct cost looked comparatively more expensive, especially as the recession pounded ad spending.
Last, but not least, Marcus explained that Move's product development approach was undisciplined, leading to resources being spread too thin in too many directions. That was reflected by the market's ongoing difficulty in categorizing which business Move was really in.
Meanwhile, U.K.-based Inuk, which had been on its own funding and product development roller-coaster, was delivering its Freewire IPTV service to about 200K university students in the UK, Ireland and Canada. Because Inuk needed to serve these students when they were off campus, it had developed a "virtual set-top box" application that duplicates on the PC the IPTV service that had traditionally been delivered via an expensive IPTV set-top box. Inuk was using Move's ABR technology to power video delivery to the PC. Recognizing potential synergies and trying to address its other issues, Move acquired Inuk in April.
Move's new positioning as a provider of IPTV video services delivered over open broadband networks essentially replicates what Inuk has been doing, except that going forward services will be offered wholesale, not retail like with Freewire. Move's strategy starts from the proposition that to get cable TV networks online requires that they be paid consistent with the norms, rather than expecting them to free and ad-supported only. It also anticipates that consumers demand not just VOD offerings, but a full linear lineup as well (as an aside, that aligns with Sezmi's thinking too). While Move will continue supporting existing customers like ABC and others, its new wholesale model is a major shift in that it uses the company's core technology to support packaged multichannel video services, instead of a la carte web-based video.
Marcus explained that Move is targeting 3 verticals: (1) telcos which haven't traditionally offered video services (or have through direct satellite partnerships), (2) broadband ISPs looking to get into the video business, and (3) existing video service providers looking for a lightweight capex approach for extending their service either for remote access (a la "TV Everywhere") or in other rooms in the house (a model which has traditionally required another set-top box and truck roll for installation).
Marcus demo'd the Freewire service to me using his PC and a large monitor, and it looks great. There's instant channel changing, HD (when available), a great looking guide and auto-DVR of every program, all in the cloud. Freewire also offers targeted advertising, and HTML-based apps like Twitter integration, etc. My caveat is that I have no idea how well the service would scale to millions of homes.
Move's new positioning puts it in the middle of tectonic video industry shifts. For example, what's the appetite of 3rd parties like telcos and ISPs for new video solutions? Will other, well-suited consumer brands like Google, Netflix, Yahoo enter the multichannel video business, and if so how? What approach will cable operators like Comcast use for emerging, "TV Everywhere" services that would benefit from Move's lightweight capex model (note Comcast said it was using Move in its 5,000 subscriber technical trial yesterday)? How will major cable TV networks expect to get compensated in the broadband era where individuals, not homes, are the new unit of measurement? How will local ISPs, over whose networks remotely-accessed video will run, expect to be compensated? It's way too early to know the answers, but if Move's technology works as intended, and its costs are reasonable, it will likely find itself in the middle of a lot of very strategic industry discussions.
Another big change is that Marcus said the company's messaging will be focused more around business cases and services than its specific technologies. That seems smart given giants like Microsoft and Adobe are closely circling these waters with lots of their own technology, which could easily swamp Move. If all this wasn't enough, Move is also in the midst of hiring a new CEO and implementing a new management team, all of which will be announced imminently. One thing Move isn't doing for now is raising additional capital, which Marcus said is not needed.
What do you think? Post a comment now.
(Note: Move Networks is a current sponsor of VideoNuze)
Categories: Broadcasters, Cable Networks, Cable TV Operators, Deals & Financings, IPTV, Technology, Telcos
Topics: ABC, Adobe, FOX, Microsoft, Move Networks
-
Nokeena Raises $6.5M from Mayfield
Nokeena Networks is announcing this morning that it has raised $6.5M from Mayfield Fund, bringing its total funding to $15M. The new funding will be used primarily for marketing and sales. Nokeena's Media Flow Director is a software appliance that combines storage, caching and network optimization to deliver high-quality video at lower cost. I noted Nokeena in my recent post about the robust ecosystem of technology companies enabling higher-quality broadband video delivery.
Categories: Deals & Financings, Technology
-
Grab Networks Raises $12M
Grab Networks has announced a new $12M round of debt and equity financing from existing investors Softbank Capital, SCP Capital, Longworth Venture Partners and Court Square Partners. Horizon Technology Finance led the venture debt piece.
I've written about Grab (formed from the merger of Anystream and Voxant) several times on VideoNuze, and have been impressed with the demos I've seen of their new hosted solution which includes, among other things, auto-generated clips, metadata creation/management and syndication. For now the foundation of the business is still Anystream's traditional licensed transcoding product, but the new end-to-end solution pushes the company far beyond this base, into what I've called the "syndicated video economy." Among others, local broadcasters are a key target market.
This round continues the financing momentum that broadband video companies have experienced despite the financial meltdown. In Q1 '09, industry companies raised over $80M, which came on top of another $80M or so in the Fall '08. Skittish investors are clearly still optimistic about broadband's potential.
(Note, at the end of June I'll be participating in a webinar Grab Networks in organizing about video syndication. More details to come shortly.)
What do you think? Post a comment now.
Categories: Deals & Financings, Technology
Topics: Grab Networks
-
VideoNuze Report Podcast #17 - May 22, 2009
Below is the 17th edition of the VideoNuze Report podcast, for May 22, 2009.
This week Daisy takes on 2 topics: how book publishers are (finally!) embracing video to promote their authors and titles, and also what NBC's local media division is doing to roll out new web sites to support its ten owned stations. They're adding lots of original content (including from 3rd parties), video, social media features and more community emphasis. No surprise syndication is a real push. Local stations have been really hammered by the recession and also by the shift to broadband distribution, so it's good to see NBC being aggressive.
Separate but related NBC.com is my focus on this week's podcast. Specifically, I add more detail to my post this week about how NBC.com is leveraging its existing online/broadband infrastructure to support its mobile video efforts by using Kiptronic, a mobile video ad insertion company.
Coincidentally, Kiptronic was just acquired by Limelight, further validating that mobile video is a rising priority for many video providers. I've been digging into mobile video and though it's still well behind the broadband adoption curve, the iPhone and other video-ready mobile devices are creating a lot of momentum. (Recall that mobile video taking off was one of my 5 predictions for '09)
For those of you celebrating the long Memorial Day weekend, and the official start of summer, enjoy! I'll see you on Tuesday.
Click here to listen to the podcast (13 minutes, 21 seconds)
Click here for previous podcasts
The VideoNuze Report is available in iTunes...subscribe today!
Categories: Broadcasters, CDNs, Deals & Financings, Mobile Video, Podcasts
Topics: Kiptronic, Limelight, NBC.com, Podcast
-
Limelight Acquires Kiptronic; Positions Itself for Mobile Video Growth
This morning Limelight announced it has acquired Kiptronic for cash and stock. Just yesterday I wrote about how Kiptronic is helping NBC.com insert ads into its mobile video streams by plugging into NBC.com's existing work flow and DART ad infrastructure.
While NBC.com is on the leading edge of blending its broadband and mobile video infrastructures, based on my conversations with other video content providers, I suggested this is going to be a significant future
 trend. David Hatfield, Limelight's SVP of Products, Marketing and Sales, who I spoke to earlier today about the Kiptronic deal, echoed that sentiment.
While mobile video is still in the early stages, David said that for "all of its customers, mobile and Internet-connected devices are top-of-mind" and that they are looking to partners like Limelight to cost-effectively address new 3 screen opportunities, as well as challenges like audience fragmentation.
David explained that having worked with Kiptronic for 3+ years, they shared a common vision of the importance of blending broadband/online infrastructure to support the mobile/Internet-connected device world. Both companies also emphasize open video ecosystems, and Limelight intends to continue supporting other CDNs that Kiptronic has been working with. As I said yesterday, the iPhone has been responsible for driving a lot of today's mobile video usage, but with other smartphones and devices coming on strong, mobile viewership is poised to broaden and intensify. With Kiptronic under its tent, Limelight will be better positioned to serve its customers' mobile needs, and augment its core CDN services.
Categories: CDNs, Deals & Financings, Mobile Video
-
EveryZing Raises $8.25M from Peacock, Lands NBCU as Biggest Customer
EveryZing, the search and publishing technology firm, is announcing this morning that it has raised a third round of $8.25M from GE/NBC's Peacock Equity Fund and existing investors, bringing its total funding to date to $22M. In conjunction with the funding NBC Universal will integrate EveryZing's four products into NBC's Media Works platform for deployment across all of NBCU's online properties. Tom Wilde, EveryZing's CEO confirmed it was a flat round and gave me some further details last Friday.
Tom believes that EveryZing is the only 3rd party technology provider that has been integrated across Media Works. This has two key benefits - first, it means EveryZing's products will be readily available to all
 NBCU properties, thereby minimizing upfront work involved with each successive deployment. And second, the pre-negotiated pricing and standing purchase order means individual properties (and EveryZing) will avoid time-consuming negotiations each time around.
I've been bullish on EveryZing in the past (here and here) as I think their focus on generating metadata for and indexing all content forms (video, audio, text and image) allows content providers to leverage consumers' huge adoption of search. With respect to video specifically, I've long thought that one of the key inhibitors of online viewership has simply been lack of robust discovery in traditional search environments (e.g. Google, Yahoo, etc.). EveryZing addresses this, essentially merging video's surging popularity with search's universal acceptance. One other key benefit this leads to is enhanced targetability of ads.
Tom's been an evangelist on these fronts, recently publishing "Is Your SEM Strategy Ready for Web 3.0," which makes very salient points about how content consumption is shifting from a traditional "container" paradigm to new "objects" paradigm. In the old model, content providers packaged their works into discreet units (e.g. newspapers, albums, etc.). More recently though the content itself has atomized into "objects", which consumers in turn package themselves (e.g. playlists, RSS feeds, etc.). Lacking their historical packaging heft, content providers must find new ways to associate objects, lest many be left undiscovered, and therefore unmonetized.
Tom explained how this notion is at play in the NBC deal. Obviously NBC has a sprawling content empire, which it wants to fully expose across all of its disparate audiences. But until now, even clearly related content hasn't always been shared with users. Worse, this means that interested ad dollars may not be able to find enough inventory to be allocated against, leaving money on the table.
With EveryZing, NBC's goal is to be able to describe and index all of its content, allowing it to drive improved discovery and monetization. In the non-linear video-on-demand world that defines the broadband video experience, my sense is that these capabilities will become more and more valuable.
What do you think? Post a comment now.
Categories: Deals & Financings, Technology
Topics: EveryZing, NBCU, Peacock Equity Fund
-
Disney to Buy Into Hulu
Here I am at BWI airport getting ready to send today's VideoNuze email and in pops the news that Disney is taking an equity stake in Hulu, bringing lots of its prized programming along. The rumor mill has swirled for a while that a deal was forthcoming, now it's here. The press release is not yet up on the Disney site. I'll have more thoughts later.
Categories: Aggregators, Broadcasters, Deals & Financings
-
FreeWheel Raises $12M Series C Round, Video Sector Stays Strong
The syndicated video ad management company FreeWheel has announced that it has raised a $12M Series C round led by new investor Foundation Capital and existing investor Battery Ventures (prior funding
 rounds have not been disclosed). The up round provides continued evidence of fundraising strength in the broadband video sector, coming on top of at least $80M raised by industry companies in Q4 '08 and Q1 '09. Doug Knopper, co-founder/co-CEO gave me some additional background this afternoon.
Funds will be used primarily for building headcount, integrating with broadband video ecosystem partners and continued product development. The company is up to 70 employees, spread between the U.S. (25 total between NYC and Silicon Valley) and China (45, all in development).
Doug echoed what industry CEOs have been telling me for months now - it's a brutal fundraising climate, but the video sector is very hot and companies with real traction are still highly sought-after. Investors recognize the shifts in consumer behavior and ad dollars and think we're still on the front end of these trends. While content investments have cooled, enabling technologies and services are still very attractive. At the NAB Show last week I got a heads up on additional financings to be unveiled soon.
FreeWheel has been very quiet about announcing customers, but Doug says there's plenty in the hopper and some news to come soon. No doubt there is given investors' continued confidence in the company.
What do you think? Post a comment now.
Categories: Advertising, Deals & Financings
Topics: Battery Ventures, Foundation Capital, FreeWheel
-
YouTube to Merge with Hulu, Entity to be Renamed Either "YouLu" or "HuTube"
In a surprising turn-of-events, VideoNuze has learned that Google will acquire Hulu and merge it with YouTube. The resulting entity will be named either 'YouLu' or 'HuTube.' The merger brings together the two most-trafficked video sites into a powerful new player.
In an interesting twist, the final acquisition price has not yet been determined. Instead, the price will be based on a new algorithm Google is creating to accurately measure just how effective Hulu is at turning its
 users' brains into 'creamy giggity-goo' as Seth MacFarlane asserts it will in the latest of Hulu's alien-inspired ads. The algorithm will actually be able to count how many more of users' brain cells die as a result of watching shows on Hulu beyond the cells that already died due to regular on-air network TV viewership.
It turns out that Hulu's positioning as an 'evil plot to destroy the world' was considered highly synergistic with Google's longstanding mantra to 'do no evil.' Google CEO Eric Schmidt revealed that the company decided some time ago to move beyond its good-guy image, saying, "Look, we got a lot of mileage out of that 'doing no evil' malarkey, but it's time to get real. We're an avaricious multi-billion company now, and all these wacky tree-hugging green initiatives our engineers keep dreaming up can't hide that." He added, "We really admire the traction Hulu is getting by turning 'evil' into a virtue and want to tap into that concept further. Those Hollywood guys beat us hands-down when it comes to creativity."
For its part, Hulu's owners' decision to merge with YouTube, for a price not yet quantifiable, can only be seen as waiving the white flag of surrender. In an email exchange between Jeff Zucker, NBCU's CEO and Peter Chernin, Fox's former CEO (who made the original Hulu deal), obtained by VideoNuze, Zucker's frustration with Hulu's distant second place status is palpable. Among other things he says, "I thought we had dumbed down our shows as much as possible, but YouTube has clearly tapped into audiences' insatiable appetite for the inane. Who would have thought that skateboard-riding cats crashing into walls would have more audience appeal than our $2 million/episode scripted dramas. There really is no accounting for taste."
In response Chernin is quoted as saying, "Rupert always thought Hulu was a small potatoes deal, not really
 capable of losing a large, exciting amount of money. On the other hand, YouTube has been a gigantic black hole for Google, so the opportunity to join forces and achieve scale at losing money together was just incredibly compelling." He added, "Plus, you have to remember, Rupert's heart is really in newspapers. He continues to think this whole Internet thing is a fad that will eventually blow over, with people returning to newspapers as their trusted source of news and propaganda. So the company is logically positioning itself to have sizable video losses to offset expected massive gains in newspaper profitability."
Meanwhile, in a meeting with employees, Hulu CEO Jason Kilar reportedly sought to put a positive spin on the merger. Employees who have Twittered the meeting say that to pump up employee enthusiasm he re-told stories of how much fun it was to originally come up with the name 'Hulu,' reportedly saying, "Look how much mileage we got of one ridiculous-sounding made-up name, just imagine the branding possibilities of the even more-ridiculous sounding names YouLu or HuTube..." Negotiations are already underway with the Chinese portal and domain parking company that own the respective URLs.
The merger left many industry analysts scratching their heads. Representative of their reaction, VideoNuze's Will Richmond said, "Geez, I never thought we'd see a more nonsensical media merger than the one between Time Warner and AOL, but I think this YouLu/HuTube thing might just be it. Let's hope it's not for real, and is just some kind of April Fool's Day joke cooked up by an industry analyst to provide some once-per-year, cheap laughs."
Categories: Aggregators, Deals & Financings
Topics: FOX, Hulu, NBCU, YouTube
-
Visible Measures $10M Series C Round Caps Solid Q1 of Investments in Broadband Video Sector
Yesterday's announcement by Visible Measures that it raised a $10M Series C round is further evidence that broadband video companies are still able to attract financing in this brutal economic climate. Here are other video sector investments I've tracked on VideoNuze in Q1 '09:
- RipCode ($12.5M) - 1/5/09
- SundaySky ($8M) - 1/6/09
- JibJab ($7.5M) - 1/08/09
- Motionbox ($6M) - 1/14/09
- Digitalsmiths (undisclosed from Cisco) - 1/26/09
- Fliqz ($6M) - 1/28/09
- Mixpo ($4M) - 2/2/09
- WhistleBox ($2.3M) - 2/9/09
- Tremor Media ($18M) - 2/19/09
- Auditude ($10.5M) - 3/11/09
Plus 7 others totaling over $80M in the Fall of '08, and no doubt others I've missed.
Visible Measures founder and CEO Brian Shin and Matt Cutler, VP, Marketing & Analytics explained to me yesterday that key to their financing was having both solid short-term traction in the form of customer acquisitions and a long-term story built around increasing transparency and accountability for the burgeoning broadband video medium. This echoes criteria I continue to hear from other industry CEOs successfully raising money in this environment.
Since I initially profiled Visible Measures last June, and then followed-up with a post about their deal with MTV Networks last September, the company has continued to build momentum. Brian said that it's now
 powering video measurement and reporting for many of the largest web properties and dozens of advertisers. Revenue is about evenly split between the two categories.
Despite its progress, Brian explained the company has maintained a relatively low profile because neither it nor its customers have wanted to publicize their activities. Brian said there are a few competitors but none that he feels are that close to offering what Visible Measures has, and he'd like to keep it that way by being low-key about their wins. Skeptics might say "a publicity-shy early-stage company? Hmm...." but knowing Brian and his team as I do, I know that's been their approach since starting the company.
Brian added that the new round, led by Northgate Capital, a fund of funds that has also does some direct investing, "presented itself" without Visible Measures out looking for it. But Brian was quick to note that he considers the company extremely fortunate, given that he believes the current environment is even tougher than the post-bubble years in 2001-2003. Northgate is a limited partner in MDV-Mohr Davidow Ventures, one of the company's two original investors, along with General Catalyst. The company has raised a total of $29M to date.
Visible Measures plans to use the new funds to accelerate product development and grow faster. Brian and Matt made repeated references to the mountain of tracking data the company is sitting on, and that many people are interested in accessing it (which I can believe). The intent is to further productize the data, though no specifics were offered.
With publishers facing more pressure than ever to monetize effectively, and advertisers' need to understand the ROI of their spending intensifying, Visible Measures is at the intersection of two very strong trends in the fast-growing broadband video industry. It's also a textbook "syndicated video economy" company, which is yet more wind at its back. I've been bullish for a while on the company's prospects and continue to be so.
What do you think? Post a comment now.
Categories: Deals & Financings, Syndicated Video Economy, Technology
Topics: General Catalyst, MDV-Mohr Davidow, MTV, Northgate Capital, Visible Measures
-
Tremor Media Raises $18 Million Further Validating Broadband Video's Impact
Tremor Media announced this morning that it has raised a Series C round of $18 million, led by Meritech Capital Partners, with participation from existing investors Canaan Partners, Masthead Venture Partners and European Founders Fund. Tremor has now raised nearly $40 million to date. Tremor's CEO Jason Glickman gave me a short update on the company yesterday and a little more background on the financing.
Tremor believes it is now the largest video ad network, with 1,400 publishing partners aggregating 137 million unique visitors per month. Tremor focuses exclusively on premium video (i.e. non user-generated)
 and Jason said the company has access to 1 billion "advertisable impressions" per month. According to Jason, this critical mass has been a big source of the company's recent success as it has been able to appeal to advertisers by segmenting its network to target certain types of users.
Jason explained that as Tremor has grown and usage of broadband video has surged, the company has increased its efforts to shift traditional TV ad dollars over. Though it's hard to know exactly what budgets ad dollars were originally earmarked for, based on the size of the RFPs Tremor's responding to, Jason thinks this shift is indeed underway. And as he correctly points out, you don't need a lot of the $70 billion that's spent on TV annually to move over to make a big impact in broadband advertising. To help compete more effectively with TV, Tremor also recently announced that it would use comScore's Post Buy and Ad Effectiveness reports to offer GRP (gross ratings points) campaign metrics.
To give some sense of Tremor's relative size, comScore reported 14.3 billion total U.S. video views in Dec. '08. Of that YouTube accounted for approximately 5.9 billion views. If you assume that somewhere between half and two-thirds of YouTube's views are UGC (and don't even consider UGC views at all other sites), then premium U.S. video views might be somewhere around 11.3-12.3 billion per month. According to these calculations, that would mean Tremor has access to around 8-9% of premium U.S. video views per month.
While acknowledging the economic downturn has created new challenges, Jason said the company has met or beat all of its metrics, is still on track for profitability in '09 and had multiple financing offers. Meritech's media and advertising experience in other portfolio companies (e.g. Facebook, Quigo, Revenue Science, etc.) was a real draw. The funding will be used to build its network, enhance its Acudeo monetization platform and continue international expansion.
There's no denying the economic pain being felt these days, but Tremor's ability to raise, coupled with other market leaders' ability to do so, is solid evidence that the broadband video market is a rare bright spot in the media landscape today. I constantly remind people that the underlying fundamentals of broadband video consumption are only increasing each month. The companies that figure out how to capitalize on these trends will still be able to raise money.
What do you think? Post a comment now.
(Note: Tremor Media is a VideoNuze sponsor)
Categories: Advertising, Deals & Financings
Topics: comScore, Meritech, Tremor Media
Posts for 'Deals & Financings'
Connect with VideoNuze
Exclusive News Roundup
- Andy Jassy says Prime Video is on track to earn ‘tens of billions of dollars’ TechCrunch
- Versant Expands Suite of FAST Channels With 4 New Selections From CNBC, E!, Oxygen Variety
- Utopai Studios hits $1B valuation with $60M raise as video AI heats up Dealroom.co
- Instagram Tests 90-Minute Horizontal Videos in Major Play for Podcasters and Creators The Hollywood Reporter
- Netflix Users Are Watching Less, Not Opening the App as Often Bloomberg
- Writers Are Making Millions Selling Short Stories to Hollywood NY Times